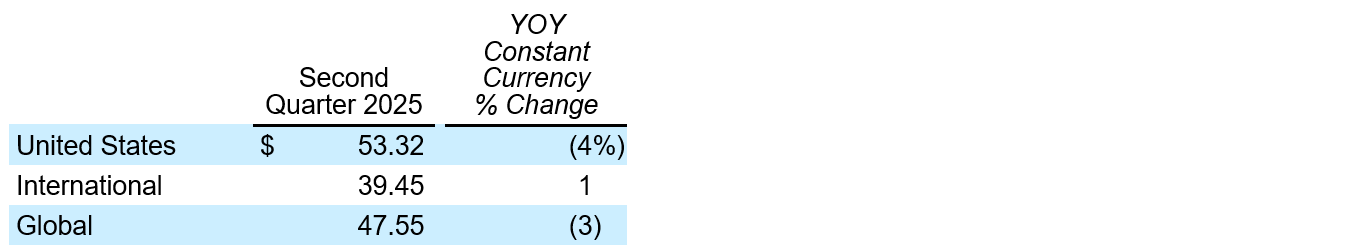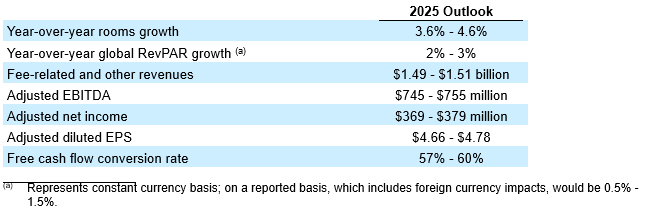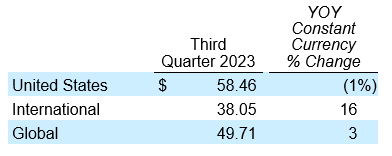Company Raises Full-Year 2026 RevPAR, Adjusted EBITDA and EPS Outlook
Grows System Size by 4% and U.S. RevPAR by 6%
PARSIPPANY, N.J., October 21, 2026 – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months ended September 30, 2026. Highlights include:
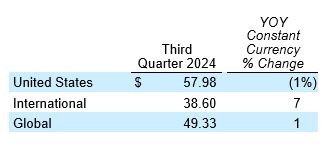
Global RevPAR grew 2% compared to third quarter 2025 in constant currency, a 4% improvement sequentially.
S. RevPAR grew 6% year-over-year, a 4% improvement sequentially.
Development pipeline grew 4% year-over-year, excluding Revo, to a record of approximately 264,000 rooms, carrying a FeePAR premium of approximately 30% to existing domestic and international systems.
Net income was $99 million and diluted EPS was $33.
Adjusted EBITDA was $207 million and adjusted diluted EPS was $1.43.
Net cash provided by operating activities was $93 million and free cash flow was $100
Returned $123 million to shareholders through $91 million of share repurchases, a 30% increase year-over-year, and quarterly cash dividends of $0.43 per share.
“Our third quarter results demonstrate our team’s continued execution and the strength of Wyndham’s asset-light, highly cash-generative business model,” said Geoff Ballotti, President and Chief Executive Officer. “We delivered broad-based U.S. RevPAR growth outperforming our initial expectations, as well as market share gains. Additionally, we grew our system and development pipeline each by 4% and increased royalties and franchise fees by 6%, as we continued to invest in industry-leading technology, loyalty and distribution initiatives that support franchisee profitability and customer satisfaction. Our strong balance sheet and cash flow generation capabilities provide significant opportunities to continue enhancing returns to our shareholders over both the short and long-term, as evidenced by our Board of Directors’ approval of a $400 million increase in our share repurchase authorization.”
Operating Results Highlights
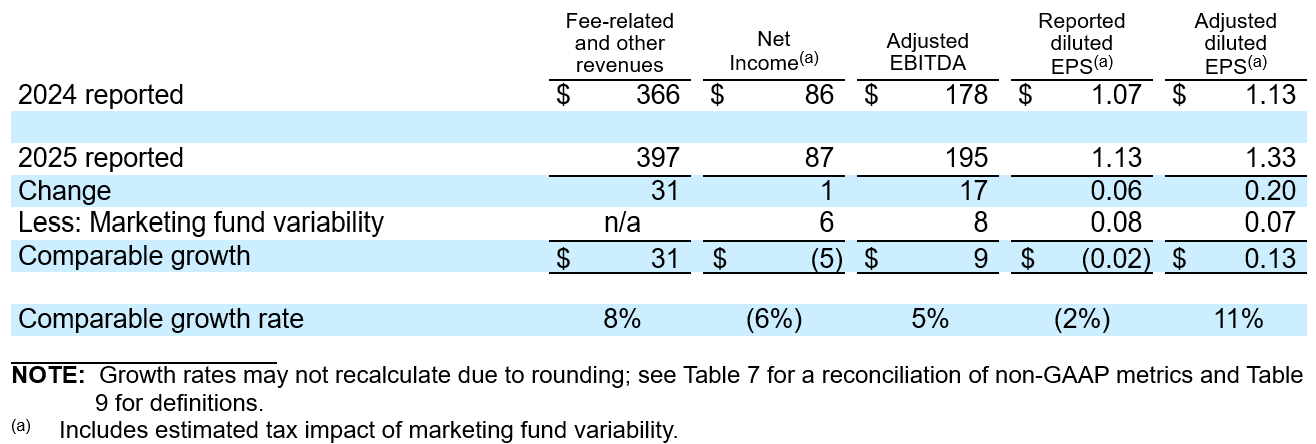
The comparability of the Company’s third quarter results is impacted by marketing fund variability. In the third quarter of 2026, marketing fund revenues exceeded expenses by $1 million, while revenues exceeded expenses by $18 million in the third quarter of last year.
The Company’s reported results and comparable basis results (adjusted to neutralize these impacts) are presented below to enhance transparency and provide a better understanding of the results of the Company’s ongoing operations.
Net revenues increased 7% to $410 million compared to $382 million in the third quarter of 2025, reflecting RevPAR and global net rooms growth, higher franchise fees, increased ancillary revenues and revenues from the Company’s two owned hotels.
Net income decreased 6% to $99 million compared to $105 million in the third quarter of 2025, primarily reflecting lower adjusted EBITDA. On a comparable basis, adjusted net income increased approximately 7% year-over-year primarily reflecting comparable basis adjusted EBITDA growth.
Adjusted EBITDA decreased 3% to $207 million compared to $213 million in the third quarter of 2025. On a comparable basis, adjusted EBITDA increased 5% primarily reflecting higher revenues, partially offset by the timing of variable costs and the lapping of one-time variable cost reductions made during the third quarter of 2025.
Diluted EPS decreased 2% to $33 compared to $1.36 in the third quarter of 2025, which reflects lower net income, partially offset with share repurchase activity.
Adjusted diluted EPS decreased 2% to $1.43 compared to $1.46 in the third quarter of 2025. On a comparable basis, adjusted diluted EPS increased approximately 9% year-over-year primarily reflecting a comparable basis increase in adjusted EBITDA and the benefit of share repurchase activity.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
RevPAR
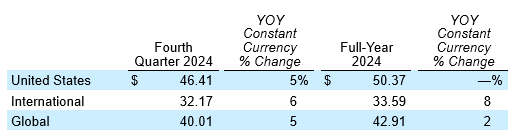
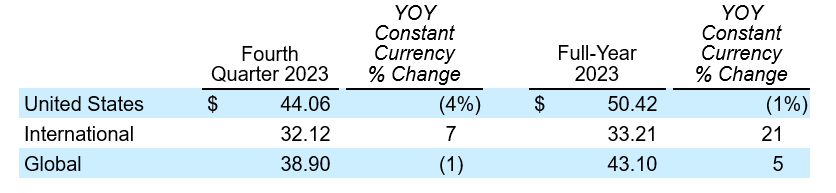
In the U.S., RevPAR improved 6% year-over-year and 4% sequentially, reflecting improved occupancy and ADR levels. Performance was broad-based across nearly all regions, highlighting the sustained strength across the Midwest and continued year-over-year and sequential growth in Texas, Florida and California.
Internationally, constant currency RevPAR declined 3% year-over-year, yet improved 4% sequentially, including year-over-year growth of 7% in Canada reflecting continued pricing and demand strength, while 5% growth in Southeast Asia and the Pacific Rim was driven by favorable ADR trends. Latin America increased 2% year-over-year and 9% sequentially primarily driven by Mexico, with favorable ADR trends and a resilient urban portfolio. EMEA increased 2% year-over-year driven by strong performance in Turkey, India and Spain and 8% sequentially reflecting recovery in Germany and stabilization across the Middle East. Growth in these regions was offset by China, where RevPAR declined 10% year-over-year as softer travel demand, particularly in Tier 2 cities, continued to pressure performance.
System Size and Development
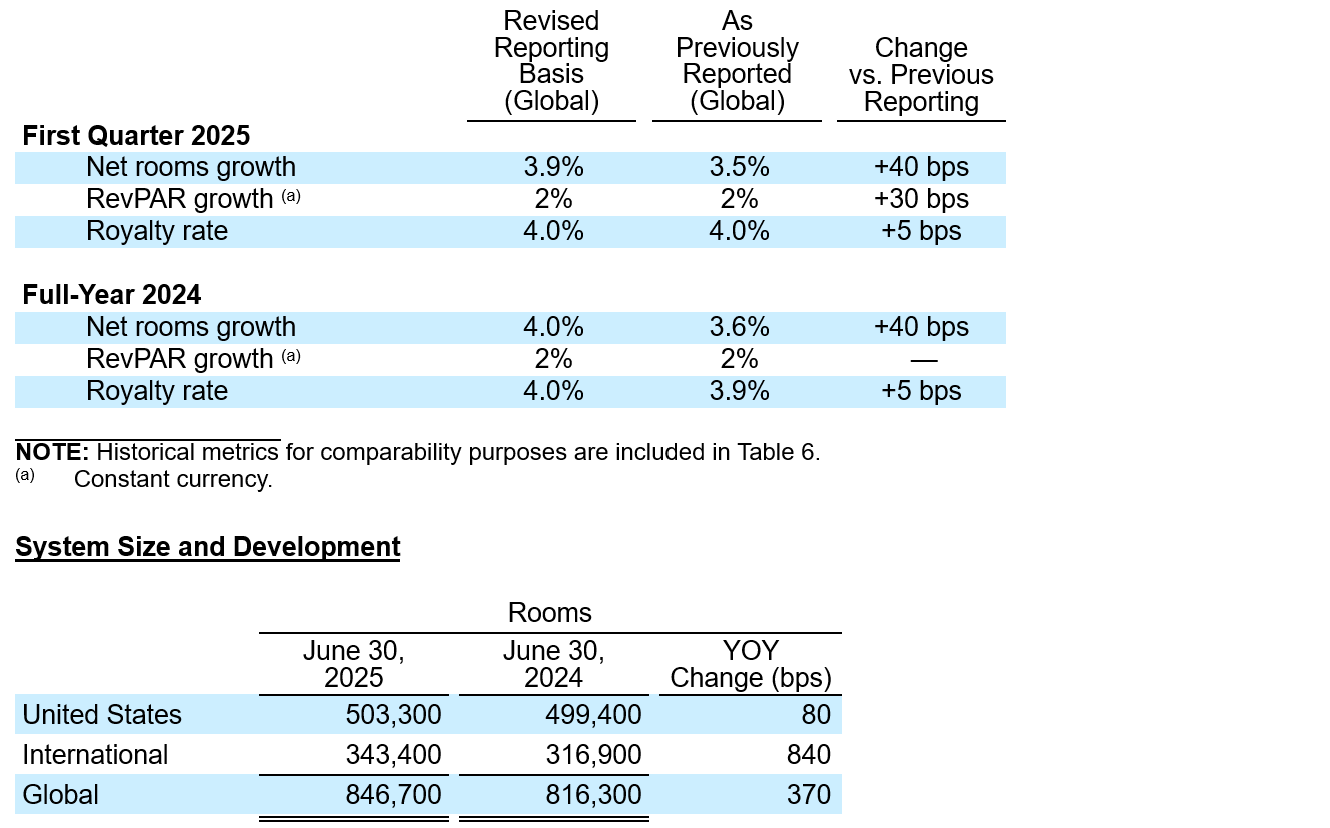
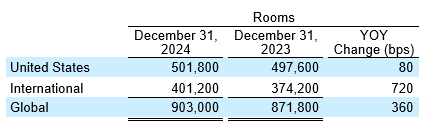
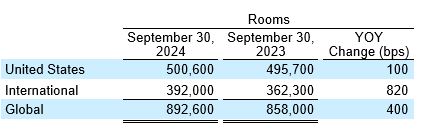
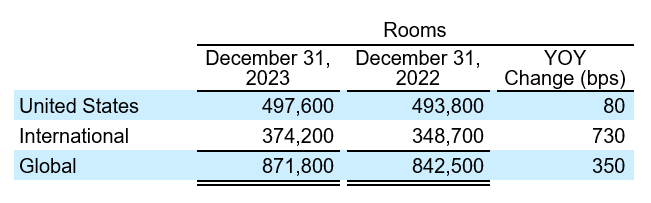
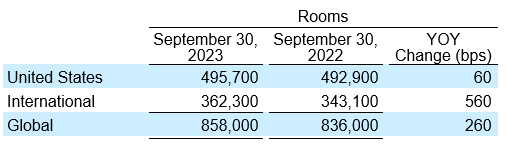
The Company’s global system, excluding Revo, grew 4%. The Company’s U.S. system grew 2% in the higher RevPAR midscale and above segments. International growth of 11% year-over-year, excluding Revo, included 12% direct-franchised growth in the Company’s Asia Pacific region and 13% growth in the Company’s higher RevPAR EMEA and Latin America regions.
As of September 30, 2026, the Company’s global development pipeline, excluding Revo, increased 4% vs. prior-year to a record-high of approximately 264,000 rooms and over 2,200 hotels. Key highlights of the Company’s pipeline include:
2% growth in the U.S. and 5% growth internationally, excluding Revo
Approximately 69% is in the midscale and above segments
Approximately 17% is in the extended stay segment
Approximately 42% is in the U.S.
Approximately 78% is new construction and approximately 35% of these projects have broken ground; rooms under construction grew 4% year-over-year
Approximately 30% FeePAR premium compared to existing domestic and international systems
Balance Sheet and Liquidity
The Company generated $93 million of net cash provided by operating activities and $100 million of free cash flow in the third quarter 2026. The Company ended the quarter with a cash balance of $71 million and $988 million in total liquidity.
The Company’s net debt leverage ratio at September 30, 2026 was 3.6 times, near the midpoint of the Company’s 3-to-4 times stated target range and in-line with expectations.
Share Repurchases and Dividends
During the third quarter, the Company repurchased approximately 1.2 million shares of its common stock for $91 million, a 30% increase year-over-year, at an average price of $73.39 per share, which represented a 5% discount to our 52-week average price. Year-to-date through September 30, the Company repurchased approximately 2.5 million shares of its common stock for $196 million. The Company’s Board of Directors recently increased the Company’s share repurchase authorization by $400 million.
The Company paid common stock dividends of $32 million, or $0.43 per share, during the third quarter 2026.
Outlook
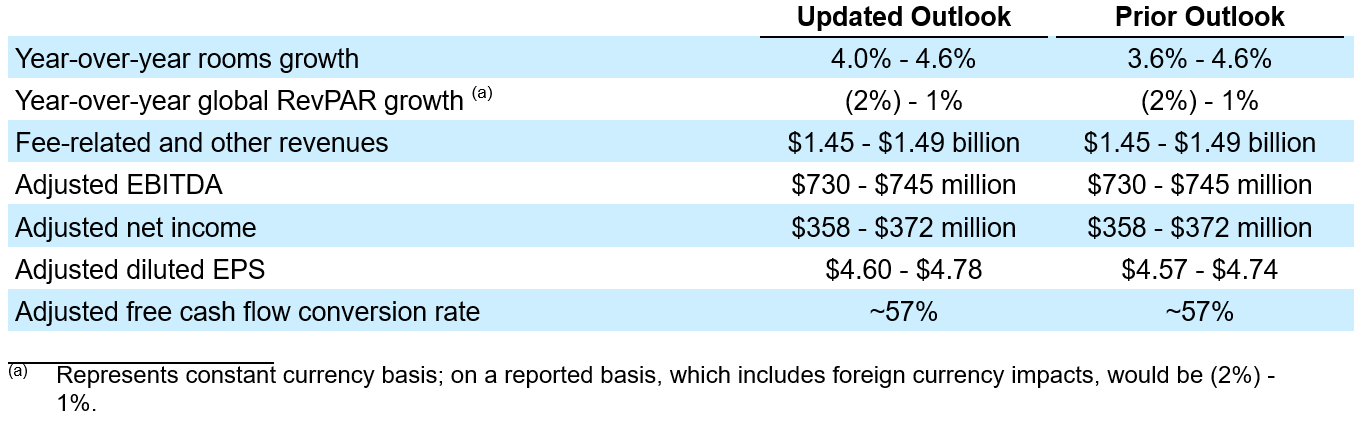
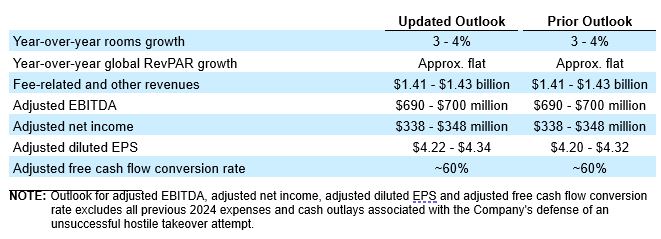
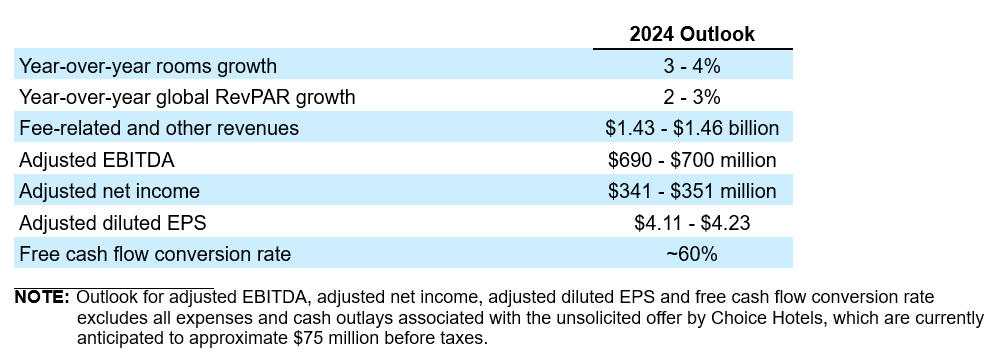
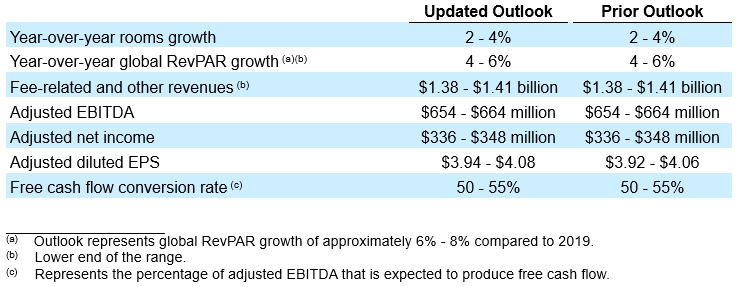
The Company is updating its full-year outlook as follows:
The Company expects marketing fund revenues to roughly equal expenses during full-year 2026 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information
Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, October 22, 2026 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 343-4136 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on October 22, 2026. A telephone replay will be available for approximately ten days beginning at noon ET on October 22, 2026 at 800 839-4014.
Presentation of Financial Information
Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts
Wyndham Hotels & Resorts (NYSE: WH) is one of the world’s largest hotel franchising companies with approximately 8,500 hotels across approximately 100 countries on six continents. Through its network of over 877,000 franchised and affiliated rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, ECHO Suites®, Registry Collection Hotels®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers approximately 129 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “confident,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures, which may impact decisions by consumers and businesses to use travel accommodations; global trade disputes, including with China; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the ability of franchisees to pay back loans owed to Wyndham; the impact of prior or any future impairment charges related to the credit Wyndham extends to its franchisees; the impact of war, terrorist activity, political instability or political strife; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company Raises Full-Year 2026 Outlook
Grows System Size by 4% and Development Pipeline by 4%
PARSIPPANY, N.J. (July 22, 2026) – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months ended June 30, 2026. Highlights include:
Development pipeline grew 4% year-over-year, excluding Revo, to a record of approximately 261,000 rooms, carrying a FeePAR premium of approximately 30% to existing domestic and international systems.
Net income increased 17% year-over-year to $102 million; adjusted net income increased 8% year-over-year to $111 million, or flat on a comparable basis.
Diluted EPS grew 20% to $36 and adjusted diluted EPS grew 11% year-over-year to $1.48, or 3% higher on a comparable basis.
Adjusted EBITDA increased 9% year-over-year to $212 million, or 3% higher on a comparable basis.
Net cash provided by operating activities increased 30% to $91 million and adjusted free cash flow increased 19% to $105
Returned $86 million to shareholders through $54 million of share repurchases and quarterly cash dividends of $0.43 per share.
“Our solid second-quarter results reflect the continued strength of Wyndham’s asset-light, fee-based business, bolstered by system expansion, higher ancillary revenues and accelerating U.S. RevPAR growth that exceeded our expectations — delivering comparable-basis adjusted EBITDA growth of 3%,” said Geoff Ballotti, President and Chief Executive Officer. “Record second quarter openings focused on higher FeePAR hotels in the midscale and above segments, demonstrate franchisees’ continued confidence in our brands and Wyndham’s compelling ‘Owner First’ value proposition. As domestic RevPAR trends, net rooms growth, global pipeline development and ancillary revenue streams continue to strengthen, we remain confident in our ability to deliver sustainable long-term growth and create meaningful value for our shareholders, franchisees, and guests.”
System Size and Development
During the preparation of its year-end 2025 financial statements, the Company learned that Revo, a large European franchisee, had filed for insolvency proceedings under self-administration for most of its operating entities. The Company removed all Revo-related revenue recognition from its 2026 outlook and reported results given the uncertainty on expected outcomes and collectability. In addition, the Company’s 2026 net room growth outlook also excluded any impact associated with Revo’s ongoing insolvency and, as such, the Company’s global net room growth metrics are also presented excluding Revo-related rooms.
The Company’s global system, excluding Revo, grew 4%. The Company’s U.S. system grew 10 basis points sequentially and was flat year-over-year. International growth of 10% year-over-year, excluding Revo, included 12% direct-franchised growth in the Company’s Asia Pacific region and 11% growth in the Company’s higher RevPAR EMEA and Latin America regions.
As of June 30, 2026, the Company’s global development pipeline increased 4% vs. prior-year, excluding Revo, to a record-high of approximately 261,000 rooms and over 2,200 hotels. Key highlights of the Company’s pipeline include:
2% growth in the U.S. and 5% growth internationally, excluding Revo
Approximately 69% is in the midscale and above segments
Approximately 17% is in the extended stay segment
Approximately 42% is in the U.S.
Approximately 78% is new construction and approximately 35% of these projects have broken ground; rooms under construction grew 4% year-over-year
Approximately 30% FeePAR premium compared to existing domestic and international systems
RevPAR
Second quarter global RevPAR decreased 1% in constant currency compared to 2025, reflecting 2% growth in the U.S. and a 6% decline internationally.
In the U.S., RevPAR improved 2% both year-over-year and sequentially, reflecting improved occupancy and ADR levels. Overall, U.S. RevPAR results were primarily driven by continued strength across the Midwest and both sequential and year-over-year growth in Texas, Florida and California.
Internationally, constant currency growth of 2% in Canada reflected sustained pricing power, while growth of 5% in Southeast Asia and the Pacific Rim primarily reflected improved demand. Growth in those regions was more than offset in Latin America, which declined 7% year-over-year primarily due to lower U.S. cross-border demand in Mexico, EMEA, which declined 6% year-over-year largely driven by the geopolitical conflict in the Middle East as well as softness in the performance of Revo hotels in its insolvency, and China, which declined by 5% year-over-year primarily due to continued deflationary pricing pressure.
Operating Results The comparability of the Company’s second quarter results is impacted by marketing fund variability. The Company’s reported results and comparable basis results (adjusted to neutralize these impacts) are presented below to enhance transparency and provide a better understanding of the results of the Company’s ongoing operations.
Net revenues declined 6% to $375 million compared to $397 million in the second quarter of 2025, reflecting the absence of pass-through revenues due to the Company’s global franchisee conference in May 2025. In addition, the decline reflected lower other franchise fees and the deferral of fees from Revo, which was partially offset by higher ancillary revenues, EBITDA-neutral revenues from the two Revo hotels the Company took possession of and global net rooms growth, excluding Revo, of 4%.
Net income increased 17% to $102 million compared to $87 million in the second quarter of 2025, primarily reflecting higher adjusted EBITDA and lower restructuring and other-related costs, partially offset by increased interest expense. Adjusted net income grew 8% to $111 million compared to $103 million in the second quarter of 2025.
Adjusted EBITDA increased 9% to $212 million compared to $195 million in the second quarter of 2025. This increase included a $11 million favorable impact from marketing fund variability, excluding which adjusted EBITDA increased 3% on a comparable basis, primarily reflecting lower general and administrative expenses driven largely by insurance recoveries, the timing of variable costs and higher ancillary revenues, partially offset by a decline in other franchise fees and the deferral of fees from Revo.
Diluted EPS grew 20% to $36 compared to $1.13 in the second quarter of 2025, which reflects higher net income and the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS increased 11% to $1.48 compared to $1.33 in the second quarter of 2025. This increase included a favorable impact of $0.11 per share related to marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS increased approximately 3% year-over-year primarily reflecting a comparable basis increase in adjusted EBITDA and the benefit of share repurchase activity, partially offset by increased interest expense.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity The Company generated $91 million of net cash provided by operating activities and $105 million of free cash flow in the second quarter 2026. The Company ended the quarter with a cash balance of $69 million and $1.0 billion in total liquidity.
The Company’s net debt leverage ratio at June 30, 2026 was 3.5 times, at the midpoint of the Company’s 3-to-4 times stated target range and in-line with expectations.
Share Repurchases and Dividends During the second quarter, the Company repurchased approximately 657,000 shares of its common stock for $54 million.
The Company paid common stock dividends of $32 million, or $0.43 per share, during the second quarter 2026.
Outlook The Company is updating its full-year outlook as follows:
The Company expects marketing fund revenues to roughly equal expenses during full-year 2026 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, July 23, 2026 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 343-4136 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on July 23, 2026. A telephone replay will be available for approximately ten days beginning at noon ET on July 23, 2026 at 800 839-5247.
Presentation of Financial Information Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts
Wyndham Hotels & Resorts (NYSE: WH) is one of the world’s largest hotel franchising companies with approximately 8,400 hotels across approximately 100 countries on six continents. Through its network of over 873,000 franchised and affiliated rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, ECHO Suites®, Registry Collection Hotels®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers over 126 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “confident,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures, which may impact decisions by consumers and businesses to use travel accommodations; global trade disputes, including with China; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the ability of franchisees to pay back loans owed to Wyndham; the impact of prior or any future impairment charges related to the credit Wyndham extends to its franchisees; the impact of war, terrorist activity, political instability or political strife; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company Grows System Size by 4% and Development Pipeline to Record 2,200 Hotels
U.S. RevPAR Recovery Ahead of Expectations
PARSIPPANY, N.J., April 29, 2026 – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months ended March 31, 2026. Highlights include:
System-wide rooms grew 4% year-over-year.
Awarded development contracts in the U.S. increased 8% year-over-year.
Development pipeline grew 3% year-over-year to a record of over 259,000 rooms and over 2,200 hotels.
S. RevPAR was flat year-over-year, 250 basis points ahead of midpoint of expectations.
Ancillary revenues increased 21% year-over-year.
Net income remained flat year-over-year at $61 million; adjusted net income increased 9% year-over-year to $73 million, or 6% lower on a comparable basis.
Diluted earnings per share grew 3% to $0.80 from $0.78 in the prior-year quarter and adjusted diluted EPS grew 12% year-over-year to $0.96, or 3% lower on a comparable basis.
Adjusted EBITDA increased 8% year-over-year to $156 million, or 1% lower on a comparable basis.
Net cash provided by operating activities of $42 million and free cash flow of $64
Returned $85 million to shareholders through $51 million of share repurchases and quarterly cash dividends of $0.43 per share.
Issued $650 million aggregate principal amount of 5.625% senior unsecured notes, due 2033, the net proceeds of which were primarily used to fully repay then-outstanding revolver and term loan A borrowings.
“We delivered a strong start to the year, highlighted by record-level first-quarter openings and a continued expansion of our development pipeline,” said Geoff Ballotti, president and chief executive officer. “As U.S. RevPAR in our economy and midscale segments continues to recover ahead of expectations, we approach the peak leisure summer season with increasing optimism. We’ve never been more confident in our ability to drive sustained long-term value creation for franchisees, guests and shareholders by adding high-quality, FeePAR-accretive hotels to our portfolio, growing ancillary revenues and scaling AI to further differentiate our industry-leading technology platform.”
System Size and Development
The Company’s global system grew 4%, including flat growth in the U.S., which includes the impact from the loss of legacy affiliated rooms, 12% direct-franchised growth in the Company’s Asia Pacific region and 9% growth in the Company’s higher RevPAR EMEA and Latin America regions.
As of March 31, 2026, the Company’s global development pipeline increased 3% vs. prior-year to a record-high level of over 259,000 rooms and over 2,200 hotels. Key highlights include:
3% pipeline growth in the U.S. and 2% growth internationally
Approximately 70% of the pipeline is in the midscale and above segments
Approximately 17% of the pipeline is in the extended stay segment
Approximately 43% of the pipeline is in the U.S.
Approximately 77% of the pipeline is new construction and approximately 35% of these projects have broken ground; rooms under construction grew 3% year-over-year
RevPAR
First quarter global RevPAR decreased 1% in constant currency compared to 2025, reflecting flat performance in the U.S. and a 1% decline internationally.
In the U.S., the year-over-year comparison was impacted by approximately 40 basis points of unfavorable hurricane impacts related to first quarter 2025; excluding which, RevPAR increased over 600 basis points sequentially and approximately 10 basis points year-over-year reflecting stabilized occupancy and ADR levels. Continued strength across the Midwest and growth in Texas was partially offset by performance in Florida and California, which both improved sequentially yet declined year-over-year.
Internationally, constant currency growth of 8% in Canada reflected significant pricing power and continued demand growth, while growth of 5% in Southeast Asia and the Pacific Rim and 1% in EMEA each primarily reflected improved demand. The growth in those regions was more than offset by softness in China where RevPAR improved over 500 basis points sequentially, yet declined 5% year-over-year, and Latin America, which declined 4% year-over-year primarily due to lower U.S. cross-border demand in Mexico.
Operating Results
The comparability of the Company’s first quarter results is impacted by marketing fund variability. The Company’s reported results and comparable-basis results (adjusted to neutralize these impacts) are presented below to enhance transparency and provide a better understanding of the results of the Company’s ongoing operations.
Net revenues grew 3% to $327 million compared to $316 million in the first quarter of 2025, reflecting a 21% increase in ancillary revenues and global net room growth of 4%, partially offset by lower other franchise fees and the deferral of fees from Revo Hospitality Group (“Revo”).
Net income remained flat at $61 million compared to the first quarter of 2025, primarily reflecting higher adjusted EBITDA offset by restructuring and other-related costs, as well as transaction-related costs resulting from the Company’s issuance of 5.625% senior unsecured notes. Adjusted net income grew 9% to $73 million compared to $67 million in the first quarter of 2025.
Adjusted EBITDA increased 8% to $156 million compared to $145million in the first quarter of 2025. This increase included a $13 million favorable impact from marketing fund variability, excluding which adjusted EBITDA declined 1% on a comparable basis. This decline primarily reflects lower royalties and franchise fees and the absence of one-time cost reductions, partially offset by increased ancillary revenues.
Diluted EPS grew 3% to $80 compared to $0.78 in the first quarter of 2025, which primarily reflects the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS increased 12% to $0.96 compared to $0.86 in the first quarter of 2025. This increase included a favorable impact of $13 per share related to marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS decreased approximately 3% year-over-year primarily reflecting a comparable basis decline in adjusted EBITDA, a marginally higher effective tax rate and increased interest expense, partially offset by the benefit of share repurchase activity.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity
The Company generated $42 million of net cash provided by operating activities and $64 million of free cash flow in the first quarter 2026. The Company ended the quarter with a cash balance of $79 million and $1.1 billion in total liquidity, which includes the effect of the February 2026 issuance of $650 million aggregate principal amount of senior unsecured notes bearing interest at 5.625%. The net proceeds from the issuance were primarily used to fully repay then-outstanding revolver and term loan A borrowings.
The Company’s net debt leverage ratio was 3.5 times at March 31, 2026, at the midpoint of the Company’s 3 to 4 times stated target range and in line with expectations.
Share Repurchases and Dividends
During the first quarter, the Company repurchased approximately 656,000 shares of its common stock for $51 million.
The Company paid common stock dividends of $34 million, or $0.43 per share, during the first quarter 2026.
Revo Update
As part of the Company’s efforts to pursue all available remedies related to Revo’s ongoing insolvency proceedings and optimize the recoverability for the Company’s shareholders, the Company exercised its rights to foreclose on and take ownership of two properties in Europe. The Company expects these properties to generate approximately $10 million of net revenues in full-year 2026 with a limited impact to earnings as the Company works to stabilize operations and implement an asset management plan to maximize value.
Outlook
The Company is updating its full-year outlook as follows:
The Company expects marketing fund revenues to roughly equal expenses during full-year 2026 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information
Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, April 30, 2026 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 343-4136 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on April 30, 2026. A telephone replay will be available for approximately ten days beginning at noon ET on April 30, 2026 at 800 695-0715.
Presentation of Financial Information
Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts
Wyndham Hotels & Resorts (NYSE: WH) is one of the world’s largest hotel franchising companies with approximately 8,400 hotels across approximately 100 countries on six continents. Through its network of approximately 869,000 franchised and affiliated rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, ECHO Suites®, Registry Collection Hotels®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers over 124 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “confident,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures, which may impact decisions by consumers and businesses to use travel accommodations; global trade disputes, including with China; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the ability of franchisees to pay back loans owed to Wyndham; the impact of prior or any future impairment charges related to the credit Wyndham extends to its franchisees; the impact of war, terrorist activity, political instability or political strife; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company increases quarterly dividend by 5% and provides full-year 2026 outlook
PARSIPPANY, N.J. (February 18, 2026) – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months and year ended December 31, 2025. Highlights include:
System-wide rooms grew 4% year-over-year.
Awarded 870 development contracts globally in 2025, an increase of 18% year-over-year and an all-time high.
Development pipeline grew 3% year-over-year and 1% sequentially to a record 259,000 rooms.
Ancillary revenues increased 15% on a full-year basis – achieving an all-time high.
Full-year 2025 diluted EPS decreased 31% to $2.50 from $61 primarily reflecting non-cash impairment and other-related charges; however, adjusted diluted EPS increased 6% to $4.58, or approximately 6% on a comparable basis.
Full-year 2025 net income decreased 33% to $193 million from $289 million primarily reflecting non-cash impairment and other-related charges; however, adjusted net income increased 2% to $353 million, or approximately 2% on a comparable basis.
Full-year 2025 adjusted EBITDA increased 3% to $718 million, or 4% on a comparable basis – in line with the Company’s expectations.
Net cash provided by operating activities of $367 million and adjusted free cash flow of $433
Returned $393million to shareholders for the full-year through $266 million of share repurchases and quarterly cash dividends of $41 per share.
Board of Directors recently authorized a 5% increase in the quarterly cash dividend to $0.43 per share beginning with the dividend expected to be declared in the first quarter 2026.
“Our teams around the world opened a record 72,000 rooms, delivered 4% global net room growth and grew our global development pipeline to a record 259,000 rooms,” said Geoff Ballotti, president and chief executive officer. “Despite continued negative U.S. RevPAR pressure, we grew full-year comparable-basis adjusted EBITDA and adjusted EPS in 2025 by 4% and 6%, respectively, generated adjusted free cash flow of more than $430 million and returned nearly $400 million to shareholders. As demand trends improve and RevPAR stabilizes, we remain confident in our long-term strategy while creating compounding value for franchisees, guests and shareholders.”
Reporting Methodology Beginning in the second quarter of 2025, the Company revised its reporting methodology to exclude the impact of all rooms under the Super 8 China master license agreement from its reported system size, RevPAR and royalty rate, and corresponding growth metrics. The Company’s financial results will continue to reflect fees due from the Super 8 master licensee in China, which contributed approximately $2 million to the Company’s full-year 2025 consolidated adjusted EBITDA.
System Size and Development
The Company’s global system grew 4%, including 1% growth in the U.S. and 7% growth in the Company’s higher RevPAR EMEA and Latin America regions.
As of December 31, 2025, the Company’s global development pipeline increased 3% vs. prior-year to a record-high level of approximately 2,200 hotels and 259,000 rooms. Key highlights include:
3% pipeline growth in both the U.S. and internationally
Approximately 70% of the pipeline is in the midscale and above segments, which grew 3% year-over-year
Approximately 17% of the pipeline is in the extended stay segment
Approximately 42% of the pipeline is in the U.S.
Approximately 77% of the pipeline is new construction and approximately 36% of these projects have broken ground; rooms under construction grew 3% year-over-year
RevPAR
Fourth quarter global RevPAR decreased 6% in constant currency compared to 2024, reflecting declines of 8% in the U.S. and 1% internationally.
In the U.S., fourth quarter results included approximately 140 basis points of unfavorable hurricane impacts; excluding which, RevPAR declined approximately 610 basis points year-over-year reflecting a 360 basis-point reduction in occupancy and a 250 basis-point decline in ADR. Softer results in Florida, Texas and California were partially offset by continued strength across the Midwest.
Internationally, constant currency growth of 7% in EMEA and 6% in Latin America, each reflected both improved demand and pricing power, while growth of 1% in Canada was driven by pricing power, partially offset by lower demand. The growth in those regions was more than offset by softness in Asia Pacific, including China where RevPAR declined 10%.
For the full-year, global RevPAR decreased 3% in constant currency compared to 2024, in line with the Company’s outlook, reflecting a 4% decline in the U.S. and flat growth internationally. U.S. results reflected a 270 basis-point reduction in occupancy and a 120 basis-point decline in ADR.
Operating Results
Fourth Quarter The comparability of the Company’s fourth quarter results is impacted by marketing fund variability. The Company’s reported results and comparable-basis results (adjusted to neutralize these impacts) are presented below to enhance transparency and provide a better understanding of the results of the Company’s ongoing operations.
Fee-related and other revenues were $334 million compared to $341 million in the fourth quarter of 2024, reflecting a 5% decline in RevPAR and lower other franchise fees, partially offset by a 19% increase in ancillary revenue and global net room growth of 4%.
The Company generated a net loss of $60 million compared to net income of $85 million in the fourth quarter of 2024, reflecting impairment and other-related costs, lower adjusted EBITDA and higher interest expense. Adjusted net income was $71 million compared to $82 million in the fourth quarter of 2024.
Adjusted EBITDA decreased 2% to $165 million compared to $168million in the fourth quarter of 2024. This decrease included a $7 million unfavorable impact from expected marketing fund variability, excluding which adjusted EBITDA grew 2% on a comparable basis. This growth primarily reflects increased ancillary revenues and cost containment measures, including both operational efficiencies and one-time variable reductions, partially offset by lower royalties and franchise fees and elevated costs associated with insurance, litigation defense and employee benefits – all of which are reflective of the broader operating environment.
The Company generated diluted loss per share of $0.80 compared to diluted earnings per share of $1.08 in the fourth quarter of 2024, which primarily reflects lower net income, partially offset by the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS decreased 11% to $0.93 compared to $1.04 in the fourth quarter of 2024. This decrease included an unfavorable impact of $07 per share related to marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS decreased approximately 4% year-over-year primarily reflecting a higher effective tax rate, as expected, as well as higher interest expense, partially offset by comparable adjusted EBITDA growth and the benefit of share repurchase activity.
Full-Year The comparability of the Company’s full-year 2025 results is impacted by marketing fund variability. The Company’s reported results and comparable-basis results (adjusted to neutralize these impacts) are presented below to enhance transparency and provide a better understanding of the results of the Company’s ongoing operations.
Fee-related and other revenues grew 2% to $1.43 billion compared to $1.40 billion in full-year 2024 which reflects a 15% increase in ancillary revenues, higher pass-through revenues due to the Company’s global franchisee conference and a 4% increase in global net room growth, partially offset by a 3% decline in RevPAR.
Net income decreased 33% to $193 million compared to $289 million in full-year 2024, reflecting higher impairment and other-related costs, higher interest expense and the absence of a benefit in connection with the reversal of a spin-off related matter, which were partially offset by higher adjusted EBITDA and lower transaction-related expenses in connection with defending an unsuccessful hostile takeover attempt. Adjusted net income was $353 million compared to $347 million in full-year 2024.
Adjusted EBITDA grew 3% to $718 million compared to $694million in full-year 2024. This increase included a $2 million unfavorable impact, as expected, from marketing fund variability, excluding which adjusted EBITDA grew 4% on a comparable basis, primarily reflecting higher revenues and cost containment measures, including both operational efficiencies and one-time variable reductions, which were partially offset by lower royalties and franchise fees, along with elevated costs associated with insurance, litigation defense and employee benefits – all of which are reflective of the broader operating environment.
Diluted earnings per share decreased 31% to $2.50 compared to $3.61 in full-year 2024, which primarily reflects lower net income, partially offset by the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS grew 6% to $4.58 compared to $4.33 in full-year 2024. This increase included an unfavorable impact of $0.02 per share, as expected, related to marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS increased approximately 6% year-over-year reflecting comparable adjusted EBITDA growth and the benefit of share repurchase activity, partially offset by higher interest expense.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity The Company generated $367 million of net cash provided by operating activities and $433 million of adjusted free cash flow in 2025. The Company ended the quarter with a cash balance of $64 million and $840 million in total liquidity.
The Company’s net debt leverage ratio was 3.5 times at December 31, 2025, at the midpoint of the Company’s 3 to 4 times stated target range and in line with expectations.
Share Repurchases and Dividends During the fourth quarter, the Company repurchased approximately 0.6 million shares of its common stock for $43 million. For the full-year 2025, the Company repurchased approximately 3.1 million shares of its common stock for $266 million.
The Company paid common stock dividends of $31 million, or $0.41 per share, during the fourth quarter 2025 for a total of $127 million, or $1.64 per share, for the full-year 2025.
For the full-year 2025, the Company returned $393 million to shareholders through share repurchases and quarterly cash dividends.
The Company’s Board of Directors recently authorized a 5% increase in the quarterly cash dividend to $0.43 per share, beginning with the dividend expected to be declared in first quarter 2026.
Impairment and Other Charges During the preparation of its year-end 2025 financial statements, the Company learned that a large European franchisee, Revo Hospitality Group (“Revo”) has filed for insolvency proceedings under self-administration for most of its operating entities.
As a result, the Company has evaluated the recoverability of the carrying value of assets associated with Revo as of December 31, 2025 and has recorded charges of $74 million within operating expenses and $48 million within impairment on the Consolidated Statements of Income (Loss) to reflect the net realizable value on the Company’s balance sheet.
Additionally, as a result of Revo’s insolvency proceedings and in the process of performing its quantitative assessments for impairment on its intangible assets, the Company determined that a portion of its Vienna House trademark and related-franchise agreements were impaired. Accordingly, the Company recorded impairment charges totaling $38 million to reduce the carrying value of those assets to their estimated fair values.
Starting in the fourth quarter of 2025, the Company began deferring all revenues related to Revo due to uncertainty around collectability. These revenues will continue to accrue and will only be recognized as revenues following a period after which collections from Revo are deemed probable. The table below includes information about revenue recognition related to Revo for the periods presented:
Outlook The Company provided the following outlook for full-year 2026:
The Company expects marketing fund revenues to roughly equal expenses during full-year 2026 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, February 19, 2026 at 8:00 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 343-4136 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on February 19, 2026. A telephone replay will be available for approximately ten days beginning at noon ET on February 19, 2026 at 800 839-1320.
Presentation of Financial Information Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts Wyndham Hotels & Resorts (NYSE: WH) is the world’s largest hotel franchising company by the number of franchised properties, with over 8,300 hotels across approximately 100 countries on six continents. Through its network of approximately 869,000 franchised and affiliated rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, ECHO Suites®, Registry Collection Hotels®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers over 122 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “confident,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures, which may impact decisions by consumers and businesses to use travel accommodations; global trade disputes, including with China; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the ability of franchisees to pay back loans owed to Wyndham; the impact of prior or any future impairment charges related to the credit Wyndham extends to its franchisees; the impact of war, terrorist activity, political instability or political strife; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company grows system size and record development pipeline each by 4%
PARSIPPANY, N.J. (October 22, 2025) – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months ended September 30, 2025. Highlights include:
System-wide rooms grew 4% year-over-year.
Awarded 204 development contracts globally, an increase of 24% year-over-year.
Development pipeline grew 4% year-over-year and 1% sequentially to a record 257,000 rooms.
Ancillary revenues increased 18% compared to third quarter 2024 and 14% on a year-to-date basis.
Diluted earnings per share increased 5% year-over-year to $36; adjusted diluted EPS grew 5% to $1.46, or increased 1% on a comparable basis.
Net income increased 3% year-over-year to $105 million; adjusted net income increased 2% to $112 million, or decreased 2% on a comparable basis.
Adjusted EBITDA increased 2% year-over-year to $213 million, or remained flat on a comparable basis.
Returned $101 million to shareholders through $70 million of share repurchases and quarterly cash dividends of $0.41 per share.
“Our third quarter results once again demonstrate the resilience of our business model and the consistent execution of our teams around the world,” said Geoff Ballotti, president and chief executive officer. “Amid a challenging macro backdrop, we delivered record year-to-date organic room openings, grew our global pipeline to another all-time high, and achieved double-digit growth in ancillary revenues – all while expanding our portfolio with high-quality, FeePAR-accretive hotels. As we continue to focus development on our strongest brands and markets, advance the industry’s leading technology and loyalty platforms and drive meaningful returns to shareholders, we’re positioning Wyndham for sustained growth and value creation well into 2026 and beyond.”
Reporting Methodology Beginning in the second quarter of 2025, the Company revised its reporting methodology to exclude the impact of all rooms under the Super 8 China master license agreement from its reported system size, RevPAR and royalty rate, and corresponding growth metrics. The Company’s financial results will continue to reflect fees due from the Super 8 master licensee in China, which contributed less than $3 million to the Company’s full-year 2024 consolidated adjusted EBITDA.
System Size and Development
The Company’s global system grew 4% including 2% growth in the higher RevPAR midscale and above segments in the U.S. and 7% growth in the higher RevPAR EMEA and Latin America regions.
On September 30, 2025, the Company’s pipeline consisted of approximately 2,180 hotels and 257,000 rooms, representing another record-high level and a 4% year-over-year increase. Key highlights include:
Awarded 204 new contracts, an increase of 24% year-over-year.
4% pipeline growth in the U.S. and 4% growth internationally
Approximately 70% of the pipeline is in the midscale and above segments, which grew 4% year-over-year
Approximately 17% of the pipeline is in the extended stay segment
Approximately 58% of the pipeline is international
Approximately 75% of the pipeline is new construction and approximately 36% of these projects have broken ground; rooms under construction grew 3% year-over-year
RevPAR
Third quarter global RevPAR decreased 5% in constant currency compared to 2024, reflecting declines of 5% in the U.S. and 2% internationally.
In the U.S., RevPAR performance reflected a 300 basis-point reduction in occupancy and a 200 basis-point decline in ADR. Softer results in Texas, Florida and California were partially offset by continued strength across the Midwest.
Internationally, the decrease was primarily driven by Asia Pacific, including China where RevPAR declined 10%, and Latin America, where RevPAR declined 5%. This was partially offset by 4% growth in the EMEA region and 8% growth in Canada, both primarily reflecting pricing power.
Third Quarter Operating Results The comparability of the Company’s third quarter results is impacted by marketing fund variability. The Company’s reported results and comparable-basis results (adjusted to neutralize these impacts) are presented below to enhance transparency and provide a better understanding of the results of the Company’s ongoing operations.
Fee-related and other revenues were $382 million compared to $394 million in third quarter 2024, reflecting a 5% decline in RevPAR and lower other franchise fees, partially offset by an 18% increase in ancillary revenue, royalty rate expansion both domestically and internationally and global net room growth of 4%.
The Company generated net income of $105 million compared to $102 million in third quarter 2024, primarily due to higher adjusted EBITDA, partially offset by higher interest expense. Adjusted net income was $112 million compared to $110 million in third quarter 2024.
Adjusted EBITDA grew 2% to $213 million compared to $208million in third quarter 2024. This increase included a $6 million favorable impact from marketing fund variability, excluding which adjusted EBITDA remained flat on a comparable basis as lower royalties and franchise fees, along with elevated costs associated with insurance, litigation defense and employee benefits – all of which are reflective of the broader operating environment – were more than offset by cost containment measures, including both operational efficiencies and one-time variable reductions.
Diluted earnings per share increased 5% to $36 compared to $1.29 in third quarter 2024. This increase primarily reflects the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS grew 5% to $1.46 compared to $1.39 in third quarter 2024. This increase included a favorable impact of $0.06 per share related to marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS increased 1% year-over-year primarily reflecting the benefit of share repurchase activity, partially offset by higher interest expense.
During third quarter 2025, the Company’s marketing fund revenues exceeded expenses by $18 million; while in third quarter 2024, the Company’s marketing fund revenues exceeded expenses by $12 million, resulting in $6 million of marketing fund variability.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity The Company generated $86 million of net cash provided by operating activities and $97 million of free cash flow in third quarter 2025. The Company ended the quarter with a cash balance of $70 million and approximately $540 million in total liquidity.
The Company’s net debt leverage ratio was 3.5 times at September 30, 2025, the midpoint of the Company’s 3 to 4 times stated target range and in line with expectations.
In October 2025, the Company refinanced its $750 million revolving credit facility, extending the maturity from April 2027 to October 2030, increasing capacity by $250 million to $1 billion, and reducing borrowing costs by 35 basis points. All other terms remain similar to the previous facility.
Share Repurchases and Dividends During the third quarter, the Company repurchased approximately 830,000 shares of its common stock for $70 million. Year-to-date through September 30, the Company repurchased approximately 2.5 million shares of its common stock for $223 million.
The Company paid common stock dividends of $31 million, or $0.41 per share, during the third quarter 2025.
Full-Year 2025 Outlook The Company is updating its full-year outlook as follows: The Company expects marketing fund expenses to exceed revenues by approximately $5 million during full-year 2025, an intentional investment the Company expects to recover in future periods.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, October 23, 2025 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 343-4136 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on October 23, 2025. A telephone replay will be available for approximately ten days beginning at noon ET on October 23, 2025 at 800 939-8292.
Presentation of Financial Information Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts Wyndham Hotels & Resorts (NYSE: WH) is the world’s largest hotel franchising company by the number of franchised properties, with approximately 8,300 hotels across approximately 100 countries on six continents. Through its network of over 855,000 rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, ECHO Suites®, Registry Collection Hotels®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers approximately 121 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “confident,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures, which may impact decisions by consumers and businesses to use travel accommodations; global trade disputes, including with China; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the ability of franchisees to pay back loans owed to Wyndham; the impact of war, terrorist activity, political instability or political strife, including the ongoing conflicts between Russia and Ukraine and conflicts in the Middle East, respectively; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company Raises Full-Year 2025 EPS Outlook
Grows Development Pipeline by 5% and System Size by 4%
PARSIPPANY, N.J. (July 23, 2025) – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months ended June 30, 2025. Highlights include:
System-wide rooms grew 4% year-over-year.
Awarded 229 development contracts globally, an increase of 40% year-over-year.
Development pipeline grew 1% sequentially and 5% year-over-year to a record 255,000 rooms.
Ancillary revenues increased 19% compared to second quarter 2024 and 13% on a year-to date basis.
Diluted earnings per share increased 6% year-over-year to $13; adjusted diluted EPS grew 18% to $1.33, or 11% on a comparable basis.
Net income increased 1% year-over-year to $87 million; adjusted net income increased 13% to $103 million, or 7% on a comparable basis.
Adjusted EBITDA increased 10% year-over-year to $195 million, or 5% on a comparable basis.
Returned $109 million to shareholders through $77 million of share repurchases and quarterly cash dividends of $0.41 per share.
“We delivered another solid quarter growing our global system by 4%, expanding our development pipeline by 5%, increasing our ancillary revenues by 19%, and continuing to execute our strategy focused on higher FeePAR segments and markets, which is driving growth in both domestic and international royalty rates,” said Geoff Ballotti, president and chief executive officer. “Record first-half openings and a 40% second quarter increase in new contracts awarded reflect strong developer confidence in Wyndham’s powerful, owner-first value proposition. Amid a softer domestic RevPAR environment, we grew comparable adjusted EBITDA by 5% and comparable adjusted EPS by 11%. We also returned nearly $110 million to shareholders this quarter — continuing to demonstrate the value-creating power of our highly cash-generative, resilient asset-light business model. With consistent development, royalty rate, and ancillary fee growth, we remain very confident in our ability to create long-term value for our shareholders, franchisees, and team members through the enduring appeal of our iconic brands.”
Revised International Reporting Basis As part of a recent operational review, the Company identified violations of its Super 8 master license agreement in China and issued a notice of default to the master licensee. Given the operational challenges of obtaining accurate information from this master licensee and the uncertain outcome of the compliance process, beginning this quarter, the Company has revised its reporting methodology to exclude the impact of all rooms (approximately 67,300 rooms as of March 31, 2025) under this master license agreement from its reported system size, RevPAR and royalty rate, and corresponding growth metrics. The Company’s financial results will continue to reflect fees due from the Super 8 master licensee in China, which contributed less than $3 million to the Company’s full-year 2024 consolidated adjusted EBITDA.
To provide further context, the following table reflects the impact on the Company’s global growth metrics as a result of the exclusion of its Super 8 master license agreement in China:
The Company’s global system grew 4% including 3% growth in the higher RevPAR midscale and above segments in the U.S. and 5% growth in the higher RevPAR EMEA and Latin America regions.
On June 30, 2025, the Company’s pipeline consisted of approximately 2,150 hotels and 255,000 rooms, representing another record-high level and a 5% year-over-year increase. Key highlights include:
Awarded 229 new contracts, an increase of 40% year-over-year.
6% pipeline growth in the U.S. and 4% growth internationally
Approximately 70% of the pipeline is in the midscale and above segments, which grew 5% year-over-year
Approximately 17% of the pipeline is in the extended stay segment
Approximately 58% of the pipeline is international
Approximately 76% of the pipeline is new construction and approximately 35% of these projects have broken ground
RevPAR
Second quarter global RevPAR decreased 3% in constant currency compared to 2024, reflecting a 4% decline in the U.S. and 1% growth internationally.
In the U.S., second quarter results included approximately 150 basis points of unfavorable impacts from the timing of the Easter holiday and the 2024 solar eclipse. Excluding these impacts, the Company’s U.S. RevPAR declined approximately 2.3% year-over-year, driven by softer demand, partially offset by a modest increase in pricing.
Internationally, RevPAR results were driven by continued pricing power, offset by a decline in occupancy. The Company continued to see strong performance in its EMEA and Latin America regions, with year-over-year growth of 7% and 18%, respectively, reflecting robust pricing power in both regions. The Company’s Canada region grew RevPAR by 7% reflecting increased room nights from Canadian guests. In China, RevPAR decreased 8% year-over-year reflecting a decline in occupancy and continued pricing pressure.
Second Quarter Operating Results The comparability of the Company’s second quarter results is impacted by marketing fund variability. The Company’s reported results and comparable-basis results (adjusted to neutralize these impacts) are presented below to enhance transparency and provide a better understanding of the results of the Company’s ongoing operations.
Fee-related and other revenues grew 8% to $397 million compared to $366 million in second quarter 2024, which reflects a 19% increase in ancillary revenues, higher royalties and franchise fees, as well as higher pass-through revenues due to the Company’s global franchisee conference in May.
The Company generated net income of $87 million, a 1% increase compared to second quarter 2024, as higher adjusted EBITDA and lower transaction-related expenses were partially offset by the absence of a benefit in connection with the reversal of a spin-off related matter, higher restructuring costs, and increased interest expense. Adjusted net income grew 13% to $103 million compared to $91 million in second quarter 2024.
Adjusted EBITDA grew 10% to $195 million compared to $178million in second quarter 2024. This increase included an $8 million favorable impact from marketing fund variability, excluding which adjusted EBITDA grew 5% on a comparable basis, primarily reflecting increased ancillary revenues, as well as higher royalties and franchise fees, partially offset by higher operating expenses primarily related to growth in the Company’s credit card program and the absence of a benefit from insurance recoveries.
Diluted earnings per share increased 6% to $13 compared to $1.07 in second quarter 2024. This increase primarily reflects the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS grew 18% to $1.33 compared to $1.13 in second quarter 2024. This increase included a favorable impact of $0.07 per share related to marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS increased approximately 11% year-over-year, reflecting comparable adjusted EBITDA growth, the benefit of share repurchase activity and lower depreciation and amortization, partially offset by higher interest expense.
During second quarter 2025, the Company’s marketing fund revenues exceeded expenses by $3 million; while in second quarter 2024, the Company’s marketing fund expenses exceeded revenues by $5 million, resulting in $8 million of marketing fund variability.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity The Company generated $70 million of net cash provided by operating activities and $88 million of adjusted free cash flow in second quarter 2025. The Company ended the quarter with a cash balance of $50 million and approximately $580 million in total liquidity.
The Company’s net debt leverage ratio was 3.5 times at June 30, 2025, the midpoint of the Company’s 3 to 4 times stated target range and in line with expectations.
Share Repurchases and Dividends During the second quarter, the Company repurchased approximately 923,000 shares of its common stock for $77 million.
The Company paid common stock dividends of $32 million, or $0.41 per share, during the second quarter 2025.
Full-Year 2025 Outlook The Company is increasing its adjusted diluted EPS outlook to reflect the impact of second quarter share repurchase activity and increasing the low-end of its year-over-year rooms growth outlook by 40 basis points to reflect the removal of the dilutive impact from its Super 8 master licensee in China.
The Company continues to expect marketing fund revenues to approximate expenses during full-year 2025 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, July 24, 2025 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 343-4136 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on July 24, 2025. A telephone replay will be available for approximately ten days beginning at noon ET on July 24, 2025 at 800 723-8184.
Presentation of Financial Information Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts Wyndham Hotels & Resorts (NYSE: WH) is the world’s largest hotel franchising company by the number of franchised properties, with approximately 8,300 hotels across approximately 100 countries on six continents. Through its network of approximately 847,000 rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, ECHO Suites®, Registry Collection Hotels®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers approximately 120 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “confident,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures, which may impact decisions by consumers and businesses to use travel accommodations; global trade disputes, including with China; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the impact of war, terrorist activity, political instability or political strife, including the ongoing conflicts between Russia and Ukraine and conflicts in the Middle East, respectively; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company Increases Quarterly Dividend by 8% and Provides Full-Year 2025 Outlook
PARSIPPANY, N.J., February 12, 2025 – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months and year ended December 31, 2024. Highlights include:
Global RevPAR grew 5% compared to fourth quarter 2023 in constant currency, a 400 basis point improvement sequentially; full-year global RevPAR grew 2% year-over-year in constant currency.
U.S. RevPAR grew 5% compared to fourth quarter 2023, a 600 basis point improvement sequentially; full-year U.S. RevPAR was flat.
System-wide rooms grew 4% year-over-year.
Opened a record 68,700 rooms globally, representing 4% year-over-year growth, including nearly 28,000 in the U.S., which also grew 4% year-over-year.
Global retention rate reaches record level at 95.7%.
Development pipeline grew 2% sequentially and 5% year-over-year to a record 252,000 rooms.
Fourth quarter diluted earnings per share increased 80% to $1.08 and adjusted diluted EPS grew 14% to $1.04, or approximately 18% on a comparable basis; full-year 2024 diluted earnings per share increased 6% to $3.61 and adjusted diluted EPS grew 8% to $4.33, or approximately 10% on a comparable basis.
Fourth quarter net income increased 70% to $85 million and adjusted net income increased 9% to $82 million, or approximately 13% on a comparable basis; full-year 2024 net income was $289 million, or flat year-over-year, and adjusted net income increased 2% to $347 million, or approximately 4% on a comparable basis.
Fourth quarter adjusted EBITDA increased 9% to $168 million, or approximately 12% on a comparable basis; full-year 2024 adjusted EBITDA increased 5% to $694 million, or approximately 7% on a comparable basis.
Returned $430 million to shareholders for the full-year through $308 million of share repurchases and quarterly cash dividends of $0.38 per share.
Board of Directors recently authorized an 8% increase in the quarterly cash dividend to $0.41 per share beginning with the dividend expected to be declared in the first quarter 2025.
“We’re proud to report a very strong finish to 2024 with net rooms growth of 4% and comparable adjusted EBITDA growth of 7%. Our team’s focus on expanding into higher FeePAR markets, growing our extended-stay footprint and unlocking new ancillary revenue streams underscore the diverse growth opportunities inherent in our asset-light, resilient business model,” said Geoff Ballotti, president and chief executive officer. “What excites us most about our future is the developer interest in, and demand for, our brands both here and overseas, reflected in a pipeline that grew another 5% to a record quarter-of-a-million rooms that will open in the coming years with significant FeePAR premiums compared to our existing system. This, when coupled with improving customer demand we’re seeing across both our leisure and infrastructure segments, lays a solid foundation for sustained momentum and meaningful value creation for our shareholders, guests, franchisees and team members for many years to come.”
System Size and Development
The Company’s global system grew 4%. Importantly, these results included 4% growth in the higher RevPAR midscale and above segments in the U.S. as well as strong growth in the Company’s higher RevPAR EMEA and Latin America regions, which grew a combined 7%. The Company also increased its retention rate by another 10 basis points year-over-year, ending the year at a record 95.7%.
On December 31, 2024, the Company’s global development pipeline consisted of approximately 2,100 hotels and 252,000 rooms, representing another record-high level and a 5% year-over-year increase. Key highlights include:
7% growth in the U.S. and 4% internationally
18th consecutive quarter of sequential pipeline growth
Approximately 70% of the pipeline is in the midscale and above segments, which grew 5% year-over-year
Approximately 17% of the pipeline is in the extended stay segment
Approximately 58% of the pipeline is international
Approximately 78% of the pipeline is new construction and approximately 35% of these projects have broken ground
RevPAR
Fourth quarter global RevPAR increased 5% in constant currency compared to 2023, reflecting 5% growth in the U.S., which accelerated throughout the quarter, and 6% growth internationally. For the full year, global RevPAR was flat compared to 2023 on a reported basis, in line with the Company’s outlook, and grew 2% in constant currency reflecting flat growth in the U.S. and 8% growth internationally.
In the U.S., fourth quarter results included 140 basis points of favorable hurricane impacts; excluding which, RevPAR grew 4% year-over-year reflecting strength in both weekday business bookings and weekend leisure demand. Overall, U.S. RevPAR improved 620 basis points sequentially from third quarter, or 480 basis points excluding hurricane impacts.
Internationally, RevPAR strength was driven by ADR growth of 6% in constant currency, while occupancy remained flat. The Company’s EMEA and Latin America regions saw the largest increases year-over-year in the fourth quarter, collectively growing 15%. RevPAR for the Company’s China region declined 11% in the fourth quarter, driven by a 10% decrease in ADR.
Operating Results
Fourth Quarter
Fee-related and other revenues grew 7% to $341 million compared to $320 million in fourth quarter 2023, which reflects higher royalties and franchise fees.
Net income grew 70% to $85 million compared to $50 million in fourth quarter 2023, reflecting higher adjusted EBITDA, as well as a lower effective tax rate and lower foreign currency impact for highly inflationary countries, which were partially offset by higher interest expense.
Adjusted EBITDA grew 9% to $168 million compared to $154million in fourth quarter 2023. This increase included a $4 million unfavorable impact from expected marketing fund variability, excluding which adjusted EBITDA grew 12% on a comparable basis, primarily reflecting higher royalties and franchise fees and margin expansion.
Diluted earnings per share grew 80% to $1.08 compared to $0.60 in fourth quarter 2023, which primarily reflects higher net income and the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS grew 14% to $1.04 compared to $0.91 in fourth quarter 2023. This increase included an unfavorable impact of $0.04 per share related to expected marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS increased approximately 18% year-over-year reflecting comparable adjusted EBITDA growth and the benefit of share repurchase activity, partially offset by higher interest expense.
During fourth quarter 2024, the Company’s marketing fund revenues exceeded expenses by $5 million; while in fourth quarter 2023, the Company’s marketing fund revenues exceeded expenses by $9 million, resulting in $4 million of marketing fund variability.
Full Year
Fee-related and other revenues grew 1% to $1.40 billion compared to $1.38 billion in full-year 2023, which included $18 million of pass-through revenues associated with the Company’s 2023 global franchisee conference, absent which, fee-related and other revenue increased 3%. This growth primarily reflects higher royalties and franchise fees and ancillary revenues.
The Company reported net income of $289 million, consistent with 2023, as higher adjusted EBITDA was offset by higher transaction-related expenses in connection with defending an unsuccessful hostile takeover attempt. Other items include higher interest expense, restructuring costs and an impairment charge, which were offset by a lower effective tax rate, the absence of foreign currency impacts from highly inflationary countries and a benefit from the reversal of a spin-off related matter.
Adjusted EBITDA grew 5% to $694 million compared to $659million in full-year 2023. This increase included a $10 million unfavorable impact, as expected, from marketing fund variability, excluding which adjusted EBITDA grew 7% on a comparable basis, primarily reflecting higher royalties and franchise fees, increased ancillary revenues and margin expansion.
Diluted earnings per share grew 6% to $3.61 compared to $3.41 in full-year 2023, which primarily reflects the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS grew 8% to $4.33 compared to $4.01 in full-year 2023. This increase included an unfavorable impact of $0.09 per share, as expected, related to marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS increased approximately 10% year-over-year reflecting comparable adjusted EBITDA growth and the benefit of share repurchase activity, partially offset by higher interest expense.
During full-year 2024, the Company’s marketing fund expenses exceeded revenues by $1 million; while in 2023, the Company’s marketing fund revenues exceeded expenses by $9 million, resulting in $10 million of marketing fund variability.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity
The Company generated $290 million of net cash provided by operating activities and $397 million of adjusted free cash flow in full-year 2024. The Company ended the quarter with a cash balance of $103 million and approximately $765 million in total liquidity.
The Company’s net debt leverage ratio was 3.4 times at December 31, 2024, just below the midpoint of the Company’s 3 to 4 times stated target range and in line with expectations.
Share Repurchases and Dividends
During the fourth quarter, the Company repurchased approximately 0.3 million shares of its common stock for $23 million. For the full-year 2024, the Company repurchased approximately 4.1 million shares of its common stock for $308 million.
The Company paid common stock dividends of $30 million, or $0.38 per share, during the fourth quarter 2024 for a total of $122 million, or $1.52 per share, for the full-year 2024.
For the full-year 2024, the Company returned $430 million to shareholders through share repurchases and quarterly cash dividends.
The Company’s Board of Directors authorized an 8% increase in the quarterly cash dividend to $0.41 per share, beginning with the dividend expected to be declared in first quarter 2025.
Outlook
The Company provided the following outlook for full-year 2025:
The Company continues to expect marketing fund revenues to equal expenses during full-year 2025 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information
Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, February 13, 2025 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 225-9448 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on February 13, 2025. A telephone replay will be available for approximately ten days beginning at noon ET on February 13, 2025 at 800 839-5127.
Presentation of Financial Information
Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts
Wyndham Hotels & Resorts (NYSE: WH) is the world’s largest hotel franchising company by the number of franchised properties, with approximately 9,300 hotels across over 95 countries on six continents. Through its network of approximately 903,000 rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, ECHO Suites®, Registry Collection Hotels®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers approximately 114 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “confident,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the impact of war, terrorist activity, political instability or political strife, including the ongoing conflicts between Russia and Ukraine and conflicts in the Middle East, respectively; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company Raises Full-Year 2024 EPS Outlook and Reaffirms Remaining Outlook
Grows System Size by 4% and Development Pipeline by 5%
PARSIPPANY, N.J., October 23, 2024 – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months ended September 30, 2024. Highlights include:
System-wide rooms grew 4% year-over-year.
Opened over 17,000 rooms globally, including nearly 7,000 in the U.S., which increased 15% year-over-year, and the second ECHO Suites Extended Stay by Wyndham.
Awarded 197 development contracts globally, including 95 contracts in the U.S., which increased 10% year-over-year.
Development pipeline grew 1% sequentially and 5% year-over-year to a record 248,000 rooms.
Global RevPAR grew 1% in constant currency.
Ancillary revenues increased 8% compared to third quarter 2023.
Diluted earnings per share increased 7%, to $1.29, and adjusted diluted EPS grew 6%, to $1.39, or approximately 10% on a comparable basis.
Net income was $102 million for the third quarter, a 1% decrease over the prior-year quarter; adjusted net income was $110 million, a 1% decrease over the prior-year quarter, or a 3% increase on a comparable basis.
Adjusted EBITDA increased 4% compared with the prior-year quarter, to $208 million, or 7% on a comparable basis.
Returned $126 million to shareholders through $97 million of share repurchases and quarterly cash dividends of $0.38 per share.
“Our teams around the world once again delivered exceptional results, executing our long-term growth strategy and achieving 7% growth in comparable adjusted EBITDA fueled by continued system expansion, higher royalty rates and growth in our ancillary revenues,” said Geoff Ballotti, president and chief executive officer. “We awarded 10% more franchise contracts domestically this quarter, driving 5% growth in our development pipeline. Stabilizing RevPAR trends and improving comparisons coupled with increased infrastructure demand are expected to pave the way for improved results in the coming quarters. We remain steadfast in our long-term strategy, aimed at delivering outstanding value to our guests, franchisees and shareholders to whom we’ve returned nearly $380 million year-to-date in the form of dividends and share repurchases.”
System Size and Development
The Company’s global system grew 4%, reflecting 1% growth in the U.S. and 8% internationally. As expected, these increases included 3% growth in the higher RevPAR midscale and above segments in the U.S., as well as strong growth in the Company’s EMEA and Latin America regions, which each grew 11%. The Company continued to improve its retention rate and remains solidly on track to achieve its net room growth outlook of 3 to 4% for the full year 2024.
On September 30, 2024, the Company’s global development pipeline consisted of approximately 2,100 hotels and 248,000 rooms, representing another record-high level and a 5% year-over-year increase. Key highlights include:
7% growth in the U.S. and 3% internationally
17th consecutive quarter of sequential pipeline growth
Approximately 70% of the pipeline is in the midscale and above segments, which grew 6% year-over-year
Approximately 14% of the pipeline represents ECHO Suites Extended Stay by Wyndham for which the Company has awarded a total of 283 contracts since its launch.
Approximately 58% of the pipeline is international
Approximately 79% of the pipeline is new construction and approximately 35% of these projects have broken ground
During the third quarter of 2024, the Company awarded 197 new contracts, including 95 contracts in the U.S., which increased 10% year-over-year.
RevPAR
Third quarter global RevPAR increased 1% in constant currency compared to 2023, reflecting a 1% decline in the U.S. and 7% growth internationally.
In the U.S., RevPAR for the Company’s midscale and above segments was unchanged year-over-year while RevPAR for its economy segment declined 2% reflecting a modest acceleration from the second quarter with a sequential improvement of 10 basis points. Additionally, the Company’s U.S. economy brands continued to strengthen their position, gaining 50 basis points of market share in the third quarter driven by performance in oil and gas markets, which grew 250 basis points in the quarter, and in the five states with the highest infrastructure bill spend, which collectively grew 80 basis points. U.S. occupancy remained consistent, highlighting the resilience of the select-service space and consumer demand for these products.
Internationally, RevPAR for the Company’s EMEA, Latin America and Canada regions collectively increased 13% due to both continued pricing power, with ADR up 11%, and occupancy growth of 2%. RevPAR for the Company’s APAC region declined 7% driven by a 2% decrease in occupancy and a 5% decrease in ADR. Importantly, the third quarter RevPAR performance for APAC represented a 500 basis point sequential improvement.
Third Quarter Operating Results
Fee-related and other revenues were $394 million compared to $400 million in third quarter 2023, which included $18 million of pass-through revenues associated with the Company’s 2023 global franchisee conference, absent which, fee-related and other revenue increased 3%. The growth in fee-related and other revenues reflects higher royalties and franchise fees and ancillary revenues.
The Company generated net income of $102 million compared to $103 million in third quarter 2023. The decrease was primarily reflective of higher interest expense, partially offset by higher adjusted EBITDA.
Adjusted EBITDA grew 4% to $208 million compared to $200million in third quarter 2023. This increase included a $5 million unfavorable impact from marketing fund variability, excluding which adjusted EBITDA grew 7% on a comparable basis, primarily reflecting higher royalties and franchise fees, increased ancillary revenues and margin expansion.
Diluted earnings per share was $1.29 compared to $1.21 in third quarter 2023. This increase primarily reflects the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS grew 6% to $1.39 compared to $1.31 in third quarter 2023. This increase included an unfavorable impact of $0.04 per share related to expected marketing fund variability (after estimated taxes). On a comparable basis, adjusted diluted EPS increased approximately 10% year-over-year reflecting comparable adjusted EBITDA growth and the benefit of share repurchase activity, partially offset by higher interest expense.
During third quarter 2024, the Company’s marketing fund revenues exceeded expenses by $12 million, in line with expectations; while in third quarter 2023, the Company’s marketing fund revenues exceeded expenses by $17 million, resulting in $5 million of marketing fund variability. The Company continues to expect marketing fund revenues to roughly equal expenses during full-year 2024.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity
The Company generated $79 million of net cash provided by operating activities and $96 million of adjusted free cash flow in third quarter 2024. The Company ended the quarter with a cash balance of $72 million and approximately $750 million in total liquidity.
The Company’s net debt leverage ratio was 3.5 times at September 30, 2024, the midpoint of the Company’s 3 to 4 times stated target range.
During the third quarter of 2024, the Company executed $350 million of new interest rate swaps on its Term Loan B Facility, which will expire in 2028. The fixed rate of the new swaps is 3.3%. As a result, the Company ended the third quarter with approximately 80% of its total debt at a fixed rate and 20% variable.
Share Repurchases and Dividends
During the third quarter, the Company repurchased approximately 1.3 million shares of its common stock for $97 million. Year-to-date through September 30, the Company repurchased approximately 3.8 million shares of its common stock for $285 million.
The Company paid common stock dividends of $29 million, or $0.38 per share, during the third quarter 2024 and $92 million, or $1.14 per share, year-to-date.
Full-Year 2024 Outlook
The Company is refining its outlook as follows:
Year-over-year growth rates for adjusted EBITDA, adjusted net income and adjusted diluted EPS are not comparable due to full-year 2023 marketing fund revenues exceeding expenses by $9 million, which substantially completed the recovery of the $49 million support the Company provided to its owners during COVID. The Company continues to expect marketing fund revenues to equal expenses during full-year 2024 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information
Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, October 24, 2024 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 579-2543 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on October 24, 2024. A telephone replay will be available for approximately ten days beginning at noon ET on October 24, 2024 at 800 695-0715.
Presentation of Financial Information
Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts
Wyndham Hotels & Resorts (NYSE: WH) is the world’s largest hotel franchising company by the number of properties, with approximately 9,200 hotels across over 95 countries on six continents. Through its network of approximately 893,000 rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 25 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, Hawthorn Suites®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers approximately 112 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website and social media channels as means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com or on the Company’s social media channels, including the Company’s LinkedIn account which can currently be accessed at https://www.linkedin.com/company/wyndhamhotels. Accordingly, investors should monitor this section of the Company’s website and the Company’s social media channels in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to Wyndham’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. Forward-looking statements are any statements other than statements of historical fact, including those that convey management’s expectations as to the future based on plans, estimates and projections at the time Wyndham makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “predict,” “intend,” “goal,” “future,” “forward,” “remain,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of Wyndham to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures; global or regional health crises or pandemics including the resulting impact on Wyndham’s business, operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; Wyndham’s relationships with franchisees; the impact of war, terrorist activity, political instability or political strife, including the ongoing conflicts between Russia and Ukraine and conflicts in the Middle East, respectively; Wyndham’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to Wyndham’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and Wyndham’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in Wyndham’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. These risks and uncertainties are not the only ones Wyndham may face and additional risks may arise or become material in the future. Wyndham undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Increases Quarterly Dividend by 9%; Reiterates Full-Year 2024 Outlook
PARSIPPANY, N.J. (February 14, 2024) – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months and year ended December 31, 2023. Highlights include:
System-wide rooms grew organically by 3.5% year-over-year, a record high.
Opened a record 66,000 organic rooms, representing a year-over-year increase of 3%.
Global retention rate – including all terminations – improved another 30 basis points to a record 95.6%.
Development pipeline grew 1% sequentially and by 10% year-over-year to a record 240,000 rooms.
Grew ECHO Suites pipeline nearly 60% year-over-year with 98 new contract signings.
Signed 766 contracts for legacy brands, an increase of 8% year-over-year.
Fourth quarter diluted earnings per share of $0.60 and net income of $50 million; adjusted diluted EPS of $0.91, adjusted net income of $75 million and adjusted EBITDA of $154 million.
Full-year 2023 diluted EPS of $3.41 and net income of $289 million; adjusted diluted EPS of $4.01, adjusted net income of $341 million and adjusted EBITDA of $659 million.
Net cash provided by operating activities of $376 million and free cash flow of $339 million for the full-year.
Returned $515 million to shareholders for the full-year through $397 million of share repurchases and quarterly cash dividends of $0.35 per share.
Board of Directors recently authorized a 9% increase in the quarterly cash dividend to $0.38 per share beginning with the dividend expected to be declared in first quarter 2024.
“We are tremendously proud to report fourth quarter results that demonstrate the continued success of our global strategy and our accelerating momentum,” said Geoff Ballotti, president and chief executive officer. “Despite the distraction, uncertainty and misperceptions caused by Choice and their slanted and constant communications to our franchisee base, room openings accelerated and our global development pipeline grew by 10% to an all-time high of 240,000 rooms. Our team opened 27% more rooms than last year in the fourth quarter and we welcomed 500 new hotels to our system in 2023. This, when combined with our improving franchisee engagement and record retention rate, drove the best organic system growth we’ve ever achieved. We grew comparable adjusted EBITDA by 6% and returned over half a billion dollars to our shareholders through dividends and share repurchases. We are confident in the continued effectiveness of our growth strategy and see exceptional value-creation opportunities in the years ahead.”
System Size and Development
The Company’s global system grew 3.5%, marking 12 consecutive quarters of organic growth and reflecting 1% growth in the U.S. and 7% internationally. As expected, these increases included strong growth in both the higher RevPAR midscale and above segments in the U.S. and the direct franchising business in China, which grew 3% and 13%, respectively. The Company also increased its retention rate, which includes all terminations, by another 30 basis points year-over-year, ending the year at a record 95.6%.
On December 31, 2023, the Company’s global development pipeline consisted of over 1,950 hotels and approximately 240,000 rooms, representing another record-high level and a 10% year-over-year increase. Key highlights include:
14th consecutive quarter of sequential pipeline growth
8% growth in the U.S. and 11% internationally
Approximately 70% of the pipeline is in the midscale and above segments, which grew 6% year-over-year
Approximately 58% of the pipeline is international
Approximately 79% of the pipeline is new construction, of which approximately 34% has broken ground
The Company awarded 766 new contracts for its legacy brands in full-year 2023, an increase of 8% compared to full-year 2022. Additionally, the Company awarded 98 additional new contracts for its ECHO Suites brand and, as of December 31, 2023, the Company had awarded 268 contracts, or over 33,000 rooms, for the brand.
RevPAR
Fourth quarter global RevPAR declined 1% in constant currency compared to 2022 reflecting a 4% decline in the U.S. and growth of 7% internationally. For the full year, global RevPAR grew 5% in constant currency compared to 2022 reflecting a 1% decline in the U.S. and growth of 21% internationally.
The Company had achieved record-breaking RevPAR in the U.S. during the preceding year due to COVID-impacted travel patterns. Comparing to 2019 to neutralize for COVID-impacted travel patterns, U.S. RevPAR grew 10% in fourth quarter – a 120 basis point acceleration from third quarter 2023 growth – and 9% for the full year. Internationally, year-over-year RevPAR growth for both the fourth quarter and the full-year was primarily driven by higher occupancy levels. Compared to 2019, international RevPAR grew in fourth quarter and full-year by 44% and 36%, respectively, on a constant-currency basis.
Operating Results
Fourth Quarter
Fee-related and other revenues was $320 million compared to $310 million in fourth quarter 2022 reflecting global net room growth as well as higher license and ancillary fees.
The Company generated net income of $50 million compared to $56 million in fourth quarter 2022. The decrease was reflective of a higher effective tax rate, higher interest expense, foreign currency impact from hyper-inflation in Argentina and transaction-related expenses resulting from the unsolicited offer by Choice Hotels, partially offset by higher adjusted EBITDA.
Adjusted EBITDA grew 22% to $154 million from $126 million. This increase included a $21 million favorable impact from marketing fund variability, excluding which adjusted EBITDA grew 6% primarily reflecting higher fee-related and other revenues.
Diluted earnings per share was $0.60 compared to $0.63 in fourth quarter 2022. This decrease reflects lower net income, partially offset by the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS grew 26% to $0.91 per share from $0.72 per share. This increase included $0.19 per share related to the favorable marketing fund variability (after estimated taxes), excluding which adjusted diluted EPS was unchanged year-over-year as adjusted EBITDA growth and the benefit from share repurchase activity was substantially offset by higher interest expense.
During fourth quarter 2023, the Company’s marketing fund revenues exceeded expenses by $9 million; while in fourth quarter 2022, the Company’s marketing fund expenses exceeded revenues by $12 million, resulting in $21 million of marketing fund variability.
Full Year
Fee-related and other revenues was $1,384 million compared to $1,354 million in full-year 2022, which included $50 million from the Company’s select service management business and owned hotels, which were exited in 2022. On a comparable basis, fee-related and other revenues increased 6% year-over-year primarily reflecting global RevPAR and net room growth, higher license and ancillary fees and pass-through revenues associated with the Company’s global franchisee conference in September, which was held for the first time since 2019.
The Company generated net income of $289 million compared to $355 million in full-year 2022, which included $37 million from the select-service managed and owned hotels. The decrease was reflective of a higher effective tax rate, higher interest expense, foreign currency impact from hyper-inflation in Argentina and transaction-related expenses resulting from the unsolicited offer by Choice Hotels, partially offset by higher adjusted EBITDA.
Adjusted EBITDA was $659 million compared to $650 million in full-year 2022, which included $18 million from the select-service managed and owned hotels. The growth in adjusted EBITDA was further impacted by $11 million of unfavorable marketing fund variability. On a comparable basis, adjusted EBITDA increased 6% reflecting higher fee-related and other revenues.
Diluted earnings per share was $3.41 compared to $3.91 in full-year 2022, which included $0.40 per share from the select-service managed and owned hotels. This decrease reflects the lower net income, partially offset by the benefit of a lower share count due to share repurchase activity.
Adjusted diluted EPS was $4.01 per share compared to $3.96 per share in full-year 2022, which included $0.15 per share from the select-service managed and owned hotels. This growth in adjusted diluted EPS was further impacted by $0.09 per share (after estimated taxes) of unfavorable marketing fund variability. On a comparable basis, adjusted diluted EPS increased 8% year-over-year reflecting the adjusted EBITDA growth and the benefit from share repurchase activity, partially offset by higher interest expense.
During full-year 2023, the Company’s marketing fund revenues exceeded expenses by $9 million; while in 2022, the Company’s marketing fund revenues exceeded expenses by $20 million, resulting in $11 million of marketing fund variability.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
Balance Sheet and Liquidity
The Company generated $376 million of net cash provided by operating activities and free cash flow of $339 million in the full-year 2023. The Company ended the quarter with a cash balance of $66 million and approximately $650 million in total liquidity.
The Company’s net debt leverage ratio was 3.2 times at December 31, 2023, within the lower half of the Company’s 3 to 4 times stated target range.
Share Repurchases and Dividends
During the fourth quarter, the Company repurchased approximately 1.7 million shares of its common stock for $127 million. For the full-year 2023, the Company repurchased approximately 5.5 million shares of its common stock for $397 million, at an average price of $72.25, 8% lower than trading levels as of February 13th.
The Company paid common stock dividends of $28 million, or $0.35 per share, in the fourth quarter of 2023 for a total of $118 million, or $1.40 per share, for the full-year 2023.
For the full-year 2023, the Company returned $515 million to shareholders through share repurchases and quarterly cash dividends.
The Company’s Board of Directors authorized a 9% increase in the quarterly cash dividend to $0.38 per share, beginning with the dividend expected to be declared in first quarter 2024.
Full-Year 2024 Outlook
The Company provided the following outlook for full-year 2024:
Year-over-year growth rates for adjusted EBITDA, adjusted net income and adjusted diluted EPS are not comparable due to full-year 2023 marketing fund revenues exceeding expenses by $9 million, which substantially completed the recovery of the $49 million support the Company provided to its owners during COVID. The Company expects marketing revenues to equal expenses during full-year 2024 though seasonality of spend will affect the quarterly comparisons throughout the year.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, February 15, 2024 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 225-9448 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on February 15, 2024. A telephone replay will be available for approximately ten days beginning at noon ET on February 15, 2024 at 800 839-9719.
Presentation of Financial Information Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts Wyndham Hotels & Resorts (NYSE: WH) is the world’s largest hotel franchising company by the number of properties, with approximately 9,200 hotels across over 95 countries on six continents. Through its network of approximately 872,000 rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 24 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, Hawthorn Suites®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers over 106 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit https://investor.wyndhamhotels.com. The Company may use its website as a means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at www.investor.wyndhamhotels.com. Accordingly, investors should monitor this section of the Company’s website in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
For information related to Choice Hotels’ hostile offer, please visit www.staywyndham.com.
Forward-Looking Statements This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to the Company’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. The Company claims the protection of the Safe Harbor contained in the Private Securities Litigation Reform Act of 1995 for forward-looking statements (other than with respect to statements made in connection with the unsolicited exchange offer by Choice to acquire all outstanding shares of our common stock (the “Exchange Offer”)). Forward-looking statements include those that convey management’s expectations as to the future based on plans, estimates and projections at the time the Company makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “intend,” “goal,” “future,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of the Company to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, factors relating to the Exchange Offer, including actions taken by Choice in connection with such offer, actions taken by Wyndham or its stockholders in respect of the Exchange Offer or other actions or developments involving Choice, such as a potential proxy contest, the completion or failure to complete the Exchange Offer, the effects of such offer on our business, such as the cost, loss of time and disruption; general economic conditions, including inflation, higher interest rates and potential recessionary pressures; global or regional health crises or pandemics (such as the COVID-19 pandemic) including the resulting impact on the Company’s business operations, financial results, cash flows and liquidity, as well as the impact on its franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising business; the Company’s relationships with franchisees; the impact of war, terrorist activity, political instability or political strife, including the ongoing conflicts between Russia and Ukraine and between Israel and Hamas; the Company’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to the Company’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and the Company’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in the Company’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. The Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Company Raises Full-Year 2023 EPS Outlook, Grows Development Pipeline by Another 12%
PARSIPPANY, N.J., October 25, 2023 – Wyndham Hotels & Resorts (NYSE: WH) today announced results for the three months ended September 30, 2023. Highlights include:
Global RevPAR grew 3% compared to third quarter 2022 in constant currency.
System-wide rooms grew 3% year-over-year.
Development pipeline grew 4% sequentially and 12% year-over-year to a record 237,000 rooms.
Signed over 230 contracts, an increase of 8% year-over-year, including 60 new construction projects for ECHO Suites Extended Stay by Wyndham.
Returned $134 million to shareholders through $105 million of share repurchases and a quarterly cash dividend of $0.35 per share.
“We recently announced our Board of Directors unanimously rejected an unsolicited stock-and-cash proposal by Choice Hotels to acquire our company. Our Board of Directors, together with our financial and legal advisors, closely reviewed Choice’s latest proposal and determined, for multiple reasons, that it is not in the best interest of our shareholders. They remain confident that our standalone growth prospects offer superior, risk-adjusted returns to Wyndham shareholders,” said Geoff Ballotti, president and chief executive officer. “Supporting that belief are our third quarter results, which were highlighted by continued growth in global RevPAR, ongoing domestic and international organic net room growth and another 8% increase in hotel contracts awarded to franchisees driving our development pipeline to a record 1,930 hotels. Our economy brands gained market share domestically amidst a backdrop of normalizing U.S. leisure demand, and international occupancy continued to recover. Adjusted EBITDA grew in line with our expectations, we generated strong free cash flow and we returned significant capital to our shareholders. We remain focused on our growth strategy, which includes continued system expansion through our ECHO Suites by Wyndham brand and further improvements in franchisee retention, as well as the multi-year benefit expected from the U.S. infrastructure bill. We’re enthusiastic about our ability to deliver exceptional value to our shareholders, guests, franchisees and team members in the months and years ahead.”
Third Quarter Financial Results
Fee-related and other revenues was $400 million compared to $375 million in third quarter 2022 reflecting global RevPAR and net room growth, higher license and ancillary fees as well as the pass-through revenues associated with the Company’s global franchisee conference in September, which was held for the first time since 2019.
The Company generated net income of $103 million, or $1.21 per diluted share, compared to $101 million, or $1.13 per diluted share, in third quarter 2022. The increase was reflective of higher adjusted EBITDA in the Company’s hotel franchising segment and a lower effective tax rate, partially offset by higher interest expense. Adjusted diluted EPS grew 8% reflecting higher net income and a lower share count due to share repurchase activity. Adjusted EBITDA increased 5% to $200 million primarily reflecting higher fee-related and other revenues as well as marketing fund variability. During third quarter 2023, the Company’s marketing fund revenues exceeded expenses by $17 million; while in third quarter 2022, the Company’s marketing fund revenues exceeded expenses by $12 million.
Full reconciliations of GAAP results to the Company’s non-GAAP adjusted measures for all reported periods appear in the tables to this press release.
System Size
The Company’s global system grew 3%, reflecting 1% growth in the U.S. and 6% growth internationally. As expected, these increases included strong growth in both the higher RevPAR midscale and above segments in the U.S. and the direct franchising business in China, which grew 4% and 16%, respectively.
RevPAR
Third quarter global RevPAR grew by 3% in constant currency compared to 2022 reflecting a 1% decline in the U.S. and growth of 16% internationally. The Company had achieved record-breaking RevPAR in the U.S. during the preceding year due to COVID-impacted travel patterns. The Company’s U.S. economy brands gained market share of 100 basis points in the third quarter. Comparing to 2019 to neutralize for COVID-impacted travel patterns, U.S. RevPAR grew 9%, a 30 basis point acceleration from second quarter 2023 growth. International RevPAR growth was driven by higher occupancy levels and stronger pricing power in connection with COVID recovery, and compared to 2019 grew 45% on a constant-currency basis, a 120 basis point acceleration from second quarter 2023 growth.
Development
On September 30, 2023, the Company’s global development pipeline consisted of over 1,930 hotels and approximately 237,000 rooms, representing a 12% year-over-year increase, including 16% growth in the U.S.
Approximately 69% of the Company’s pipeline is in the midscale and above segments.
Approximately 58% of the Company’s development pipeline is international.
Approximately 80% of the Company’s pipeline is new construction, of which approximately 34% has broken ground.
During third quarter 2023, the Company awarded 172 new contracts for its legacy brands, an increase of 4% year-over-year. Additionally, the Company awarded 60 additional new contracts for its ECHO Suites Extended Stay by Wyndham brand and, as of September 30, 2023, the total number of contracts awarded for the brand was 265, or nearly 33,000 rooms.
Balance Sheet and Liquidity
As of September 30, 2023, the Company had $2.2 billion of long-term debt outstanding with a weighted average interest rate of 4.9%. The Company borrowed $110 million on its revolving credit facility during the third quarter and had an available borrowing capacity of $631 million after considering $9 million of outstanding letters of credit as of September 30, 2023. The Company ended the quarter with a cash balance of $79 million and approximately $710 million in total liquidity.
The Company generated net cash provided by operating activities of $77 million and free cash flow of $67 million in third quarter 2023.
The Company has pay-fixed/receive-variable interest rate swaps in place to hedge $600 million of the Term Loan B Facility, set to expire in the second quarter of 2024. During the third quarter of 2023, the Company executed $600 million of new forward starting interest rate swaps on the Term Loan B Facility, which will begin in second quarter 2024 and expire in 2028. The fixed rate of the new swaps is 3.8%.
Share Repurchases and Dividends
During the third quarter, the Company repurchased approximately 1.4 million shares of its common stock for $105 million. Year-to-date through September 30, the Company repurchased approximately 3.8 million shares of its common stock for $270 million.
The Company paid common stock dividends of $29 million, or $0.35 per share.
Rejection of Unsolicited Offer
On October 17, 2023, the Company announced that its Board of Directors unanimously rejected a highly conditional, unsolicited stock-and-cash proposal by Choice Hotels International, Inc. (“Choice”) to acquire all outstanding shares of Wyndham. Wyndham’s Board of Directors, together with its financial and legal advisors, closely reviewed Choice’s latest proposal with a nominal value of $90 per share, comprised of 45% in stock and 55% in cash, and determined that it is not in the best interest of Wyndham shareholders to accept the proposal.
Full-Year 2023 Outlook
The Company is updating its outlook as follows to reflect the impact of third quarter share repurchase activity:
Year-over-year growth rates are not comparable due to the sale of the Company’s owned hotels and the exit of its select-service management business, both of which occurred during 2022, as well as the variability in its marketing funds due to the support that the Company provided to its owners during 2020.
The Company’s expectations for full-year 2023 marketing funds contribution to adjusted EBITDA is unchanged at $10 million. The Company expects fund revenues will outpace fund expenses by approximately $11 million during the fourth quarter.
More detailed projections are available in Table 8 of this press release. The Company is providing certain financial metrics only on a non-GAAP basis because, without unreasonable efforts, it is unable to predict with reasonable certainty the occurrence or amount of all of the adjustments or other potential adjustments that may arise in the future during the forward-looking period, which can be dependent on future events that may not be reliably predicted. Based on past reported results, where one or more of these items have been applicable, such excluded items could be material, individually or in the aggregate, to the reported results.
Conference Call Information
Wyndham Hotels will hold a conference call with investors to discuss the Company’s results and outlook on Thursday, October 26, 2023 at 8:30 a.m. ET. Listeners can access the webcast live through the Company’s website at https://investor.wyndhamhotels.com. The conference call may also be accessed by dialing 800 225-9448 and providing the passcode “Wyndham”. Listeners are urged to call at least five minutes prior to the scheduled start time. An archive of this webcast will be available on the website beginning at noon ET on October 26, 2023. A telephone replay will be available for approximately ten days beginning at noon ET on October 26, 2023 at 800 839-6964.
Presentation of Financial Information
Financial information discussed in this press release includes non-GAAP measures, which include or exclude certain items. These non-GAAP measures differ from reported GAAP results and are intended to illustrate what management believes are relevant period-over-period comparisons and are helpful to investors as an additional tool for further understanding and assessing the Company’s ongoing operating performance. The Company uses these measures internally to assess its operating performance, both absolutely and in comparison to other companies, and to make day to day operating decisions, including in the evaluation of selected compensation decisions. Exclusion of items in the Company’s non-GAAP presentation should not be considered an inference that these items are unusual, infrequent or non-recurring. Full reconciliations of GAAP results to the comparable non-GAAP measures for the reported periods appear in the financial tables section of this press release.
About Wyndham Hotels & Resorts
Wyndham Hotels & Resorts (NYSE: WH) is the world’s largest hotel franchising company by the number of properties, with approximately 9,100 hotels across over 95 countries on six continents. Through its network of approximately 858,000 rooms appealing to the everyday traveler, Wyndham commands a leading presence in the economy and midscale segments of the lodging industry. The Company operates a portfolio of 24 hotel brands, including Super 8®, Days Inn®, Ramada®, Microtel®, La Quinta®, Baymont®, Wingate®, AmericInn®, Hawthorn Suites®, Trademark Collection® and Wyndham®. The Company’s award-winning Wyndham Rewards loyalty program offers approximately 105 million enrolled members the opportunity to redeem points at thousands of hotels, vacation club resorts and vacation rentals globally. For more information, visit www.wyndhamhotels.com. The Company may use its website as a means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD. Disclosures of this nature will be included on the Company’s website in the Investors section, which can currently be accessed at https://investor.wyndhamhotels.com. Accordingly, investors should monitor this section of the Company’s website in addition to following the Company’s press releases, filings submitted with the Securities and Exchange Commission and any public conference calls or webcasts.
Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the federal securities laws, including statements related to the Company’s current views and expectations with respect to its future performance and operations, including revenues, earnings, cash flow and other financial and operating measures, share repurchases and dividends and restructuring charges. The Company claims the protection of the Safe Harbor contained in the Private Securities Litigation Reform Act of 1995 for forward-looking statements. Forward-looking statements include those that convey management’s expectations as to the future based on plans, estimates and projections at the time the Company makes the statements and may be identified by words such as “will,” “expect,” “believe,” “plan,” “anticipate,” “intend,” “goal,” “future,” “outlook,” “guidance,” “target,” “objective,” “estimate,” “projection” and similar words or expressions, including the negative version of such words and expressions. Forward-looking statements involve known and unknown risks, uncertainties and other factors, which may cause the actual results, performance or achievements of the Company to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. You are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release.
Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, general economic conditions, including inflation, higher interest rates and potential recessionary pressures; the worsening of the effects from the coronavirus pandemic (“COVID-19”); COVID-19’s scope, duration, resurgence and impact on the Company’s business operations, financial results, cash flows and liquidity, as well as the impact on the Company’s franchisees, guests and team members, the hospitality industry and overall demand for and restrictions on travel the Company’s continued performance during the recovery from COVID-19 and any resurgence or mutations of the virus concerns with or threats of other pandemics, contagious diseases or health epidemics, including the effects of COVID-19; the performance of the financial and credit markets; the economic environment for the hospitality industry; operating risks associated with the hotel franchising businesses; the Company’s relationships with franchisees; the impact of war, terrorist activity, political instability or political strife, including the ongoing conflict between Russia and Ukraine; the Company’s ability to satisfy obligations and agreements under its outstanding indebtedness, including the payment of principal and interest and compliance with the covenants thereunder; risks related to the Company’s ability to obtain financing and the terms of such financing, including access to liquidity and capital; and the Company’s ability to make or pay, plans for and the timing and amount of any future share repurchases and/or dividends, as well as the risks described in the Company’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any subsequent reports filed with the Securities and Exchange Commission. The Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, subsequent events or otherwise, except as required by law.
Click Here to Close Modal
Contact Us
We value your interest in Wyndham & Resorts and welcome your comments and questions.
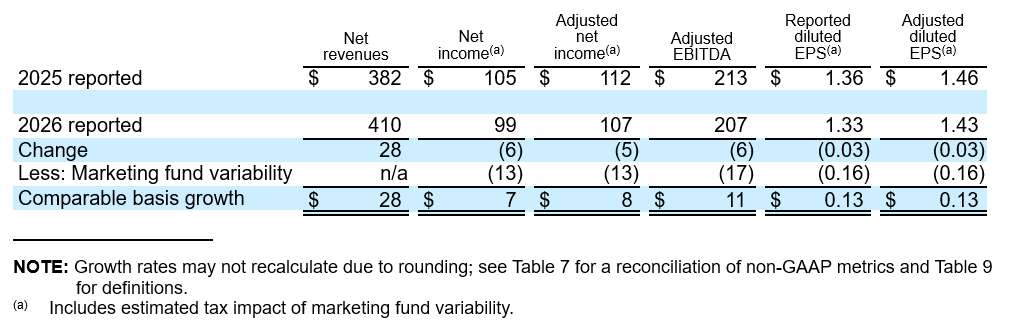
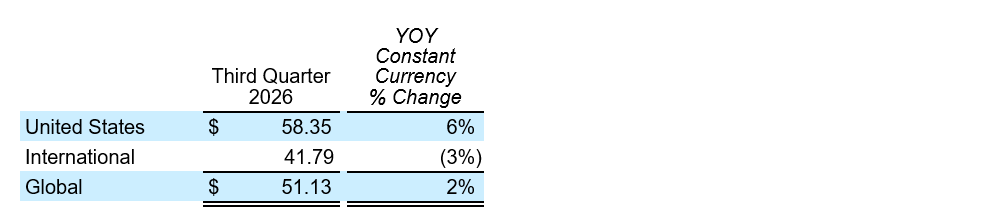
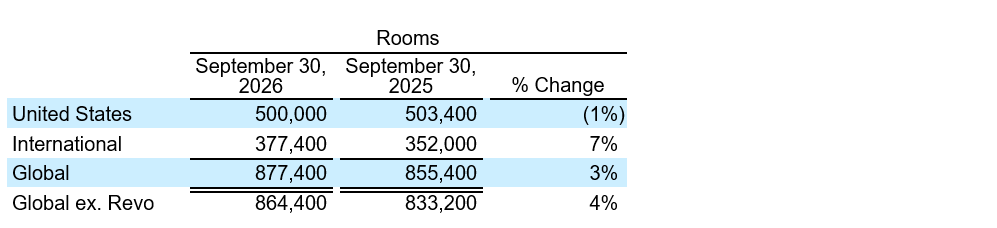
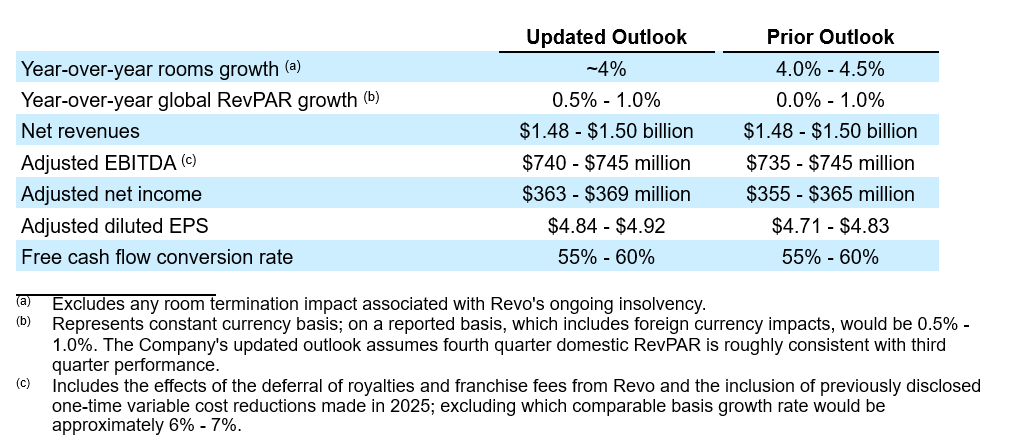
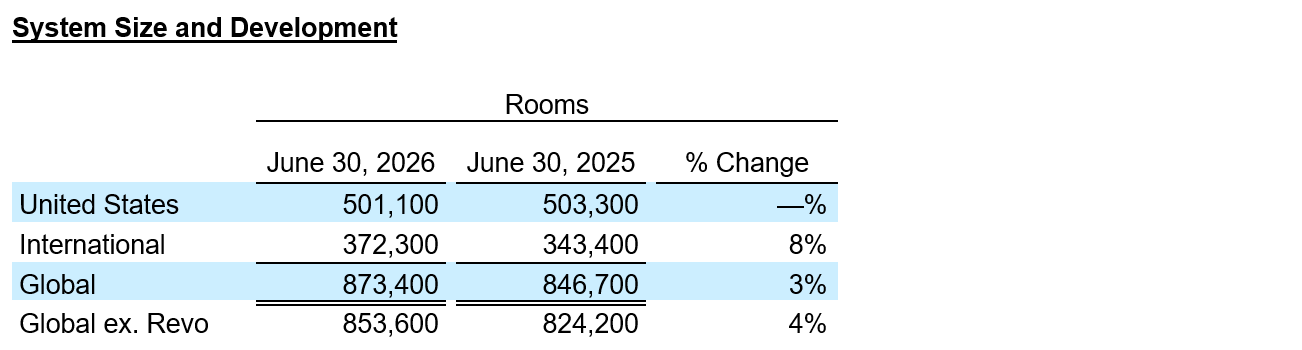
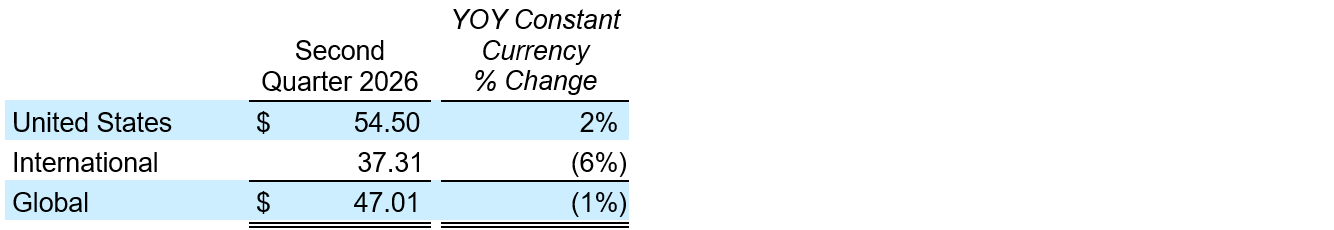
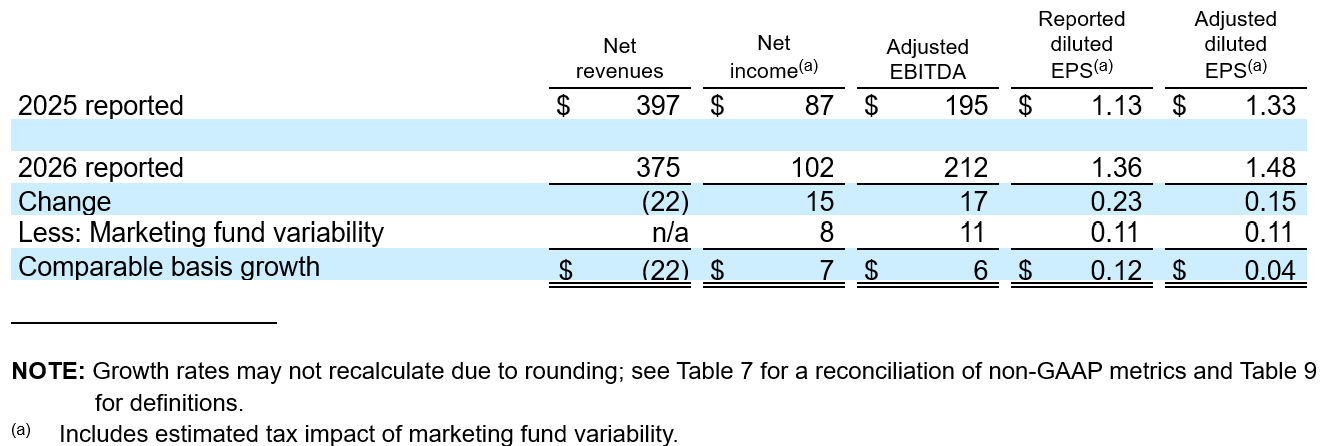
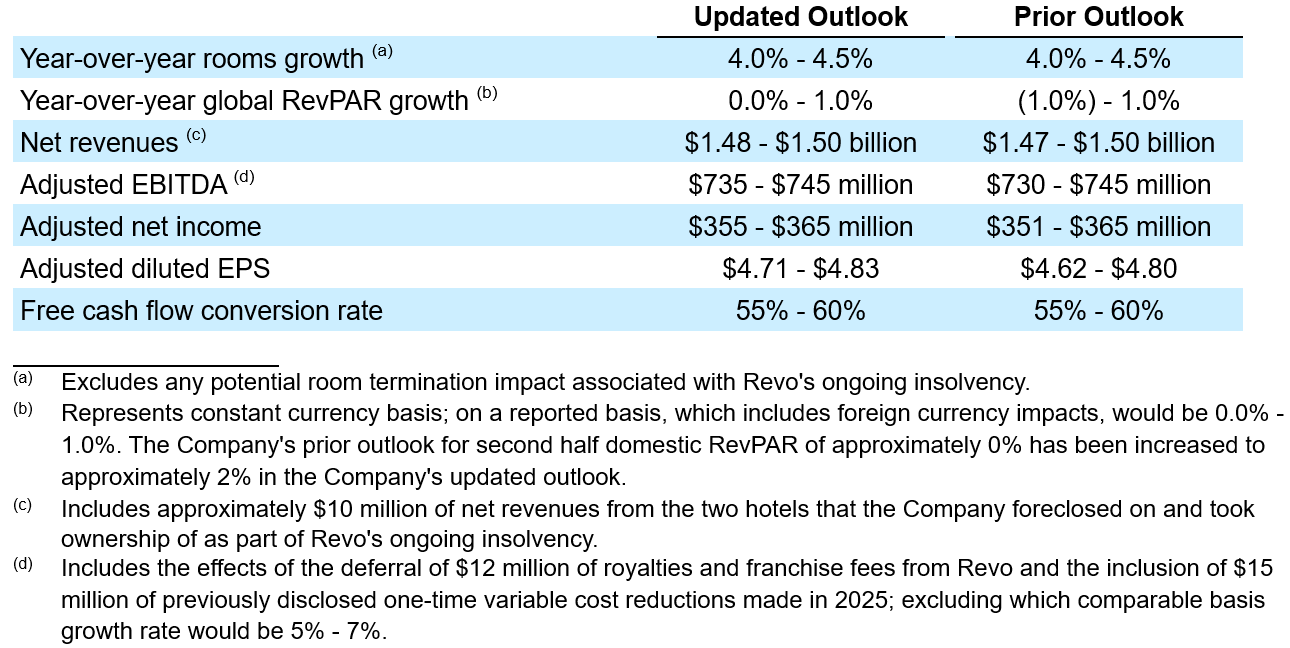
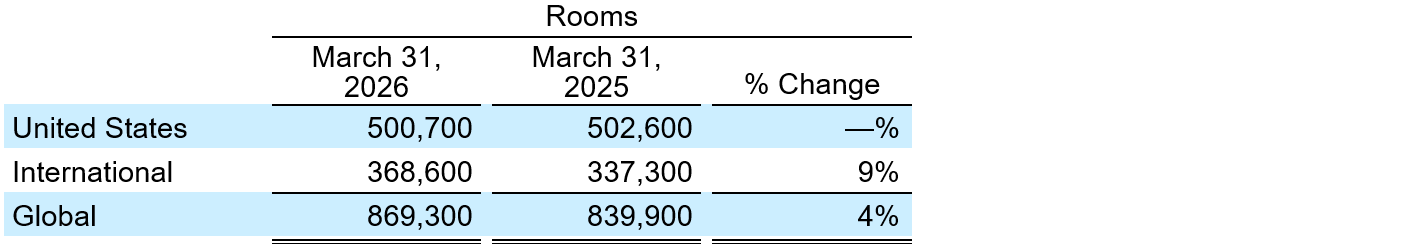
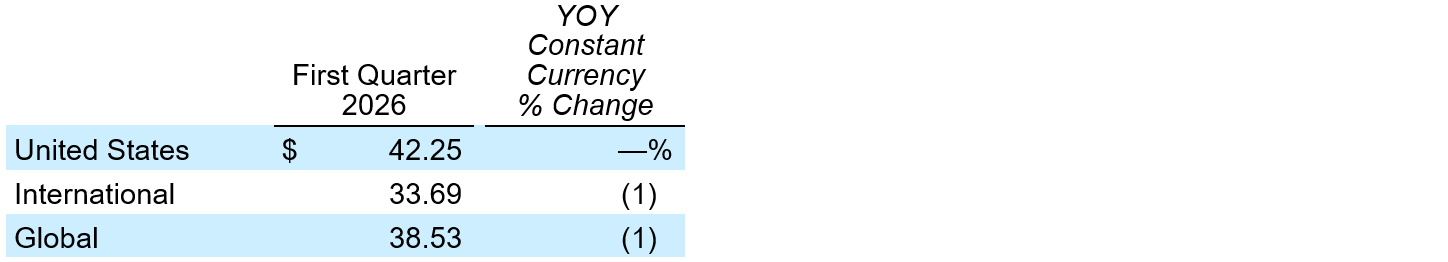
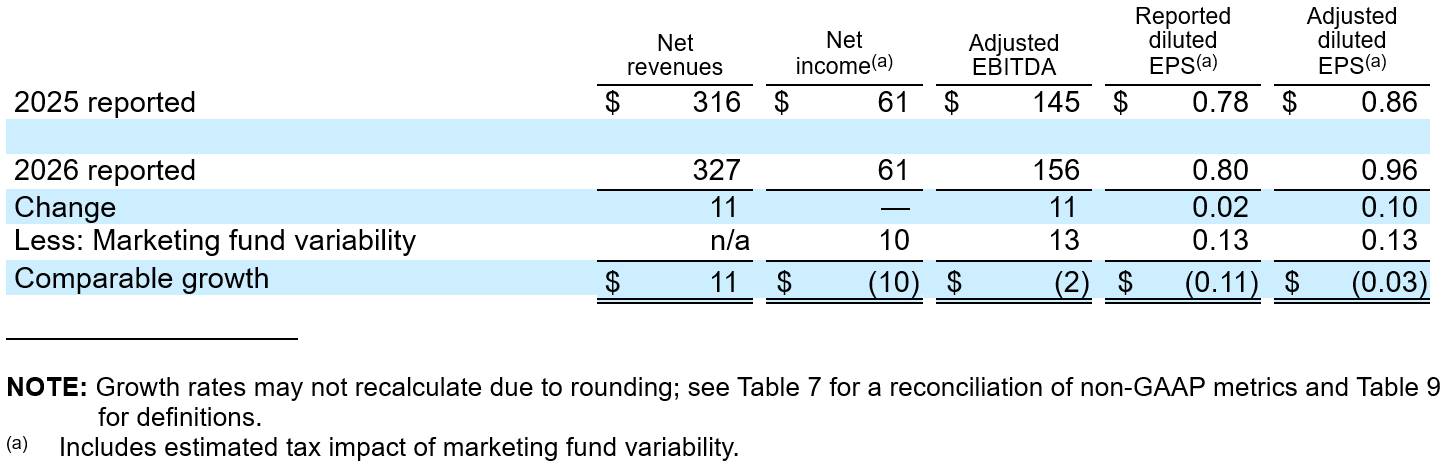
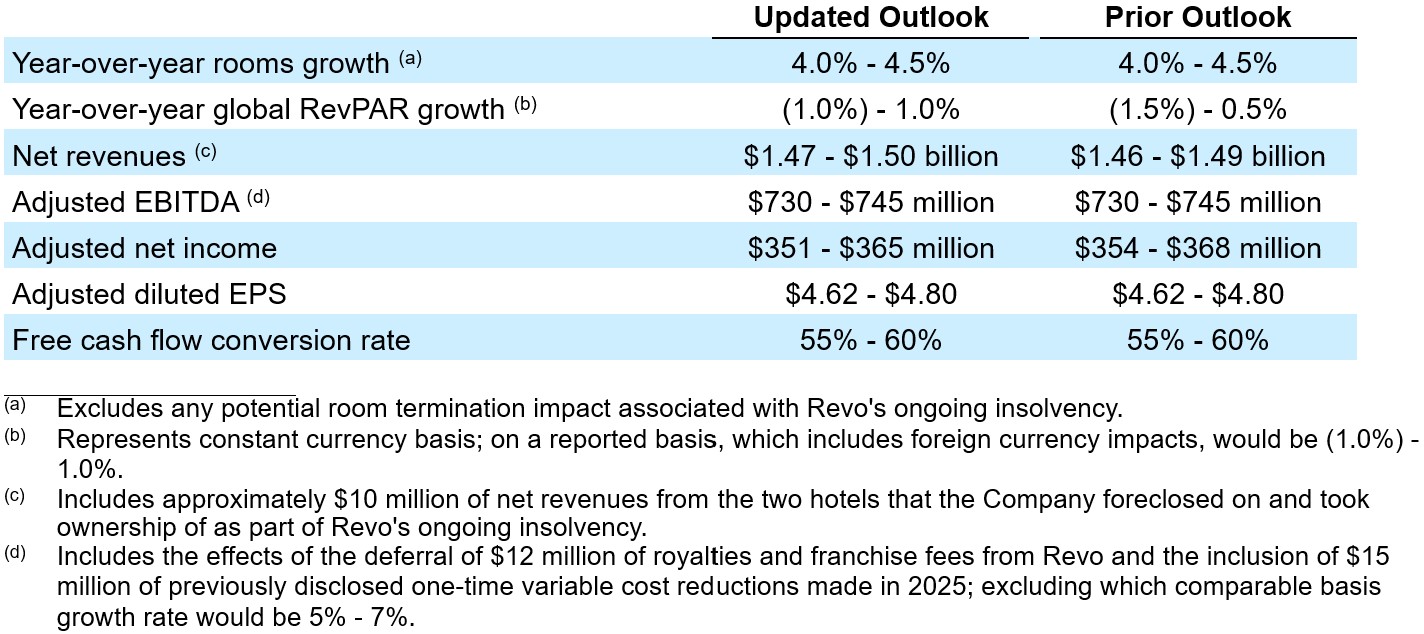
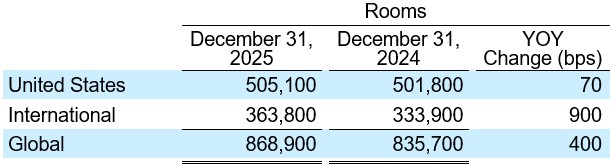
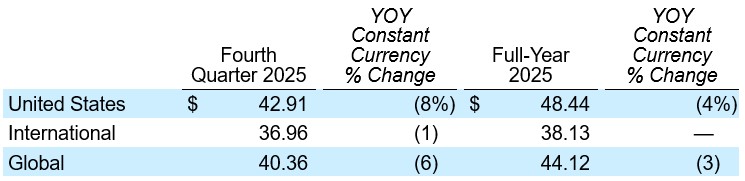
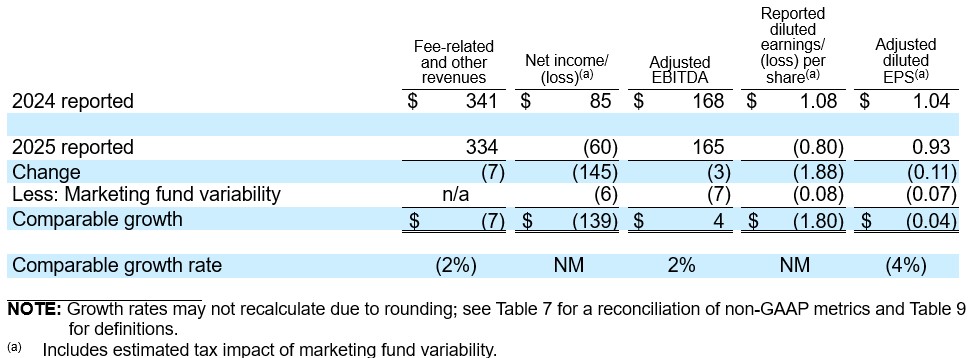
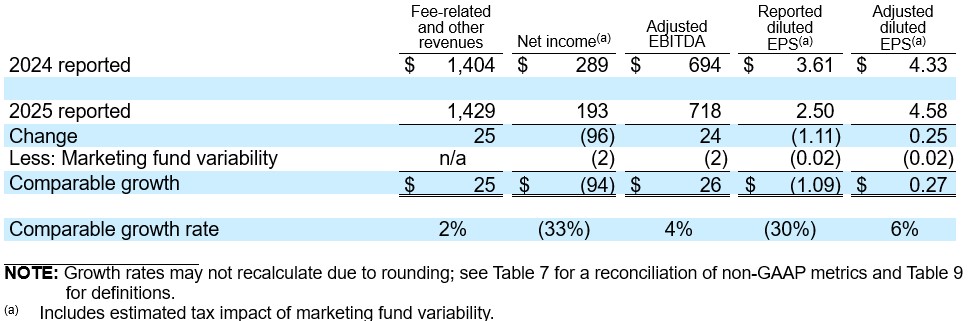
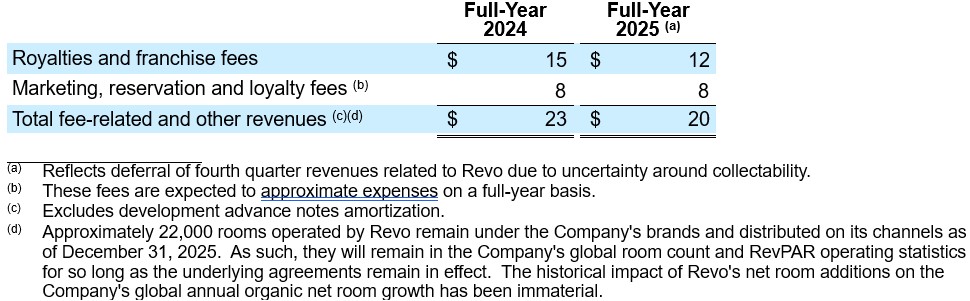
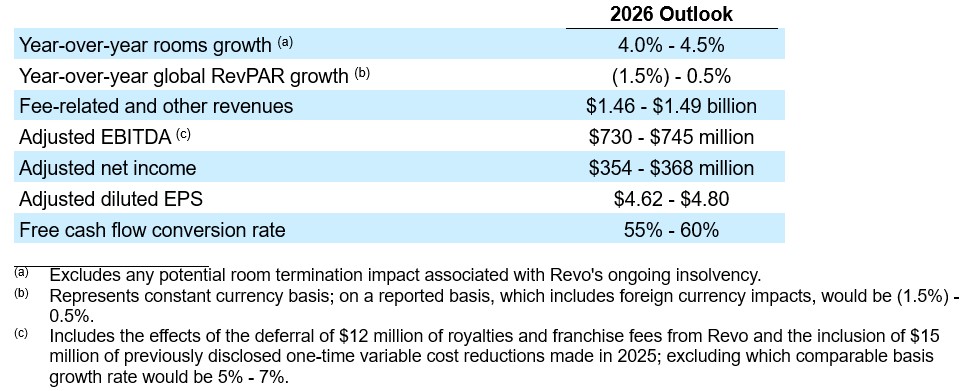
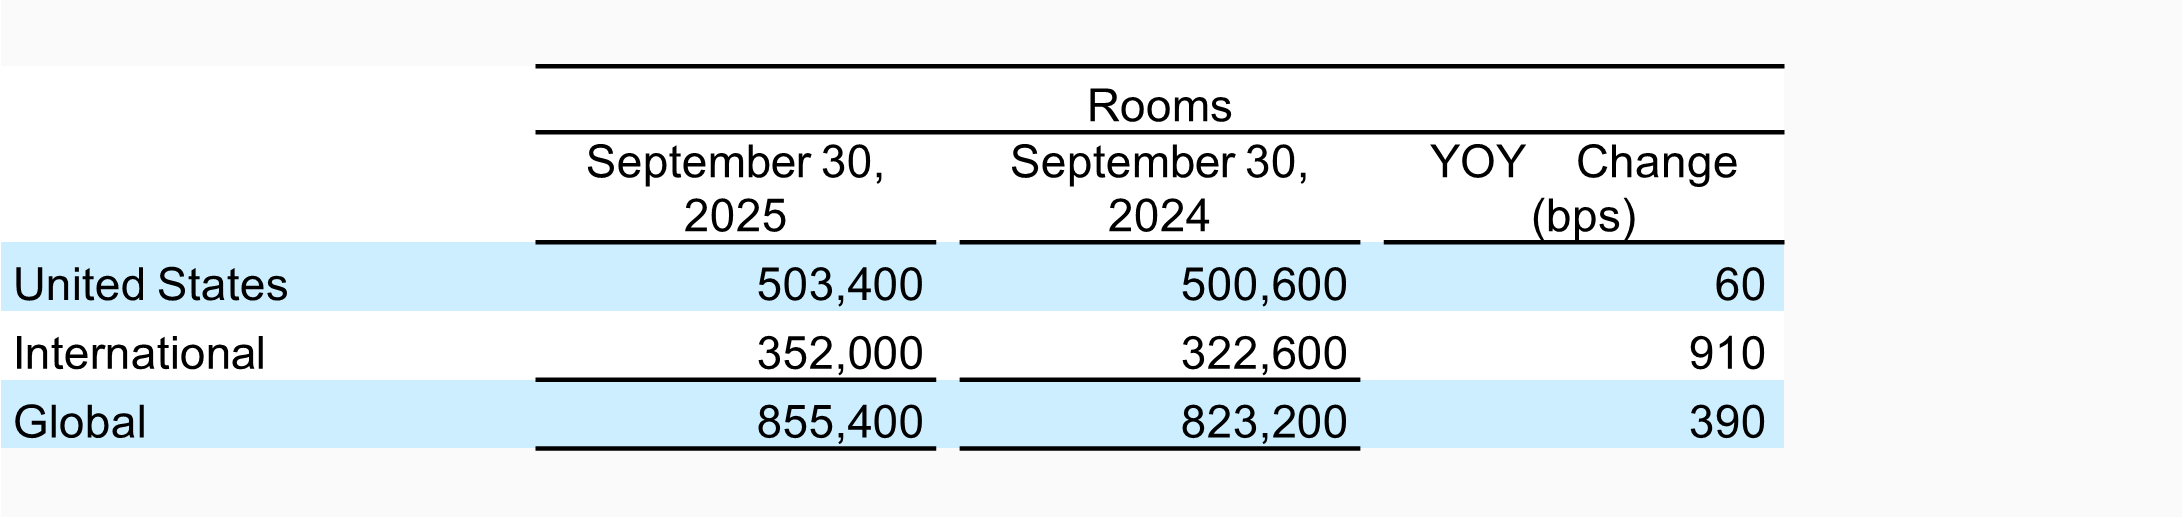
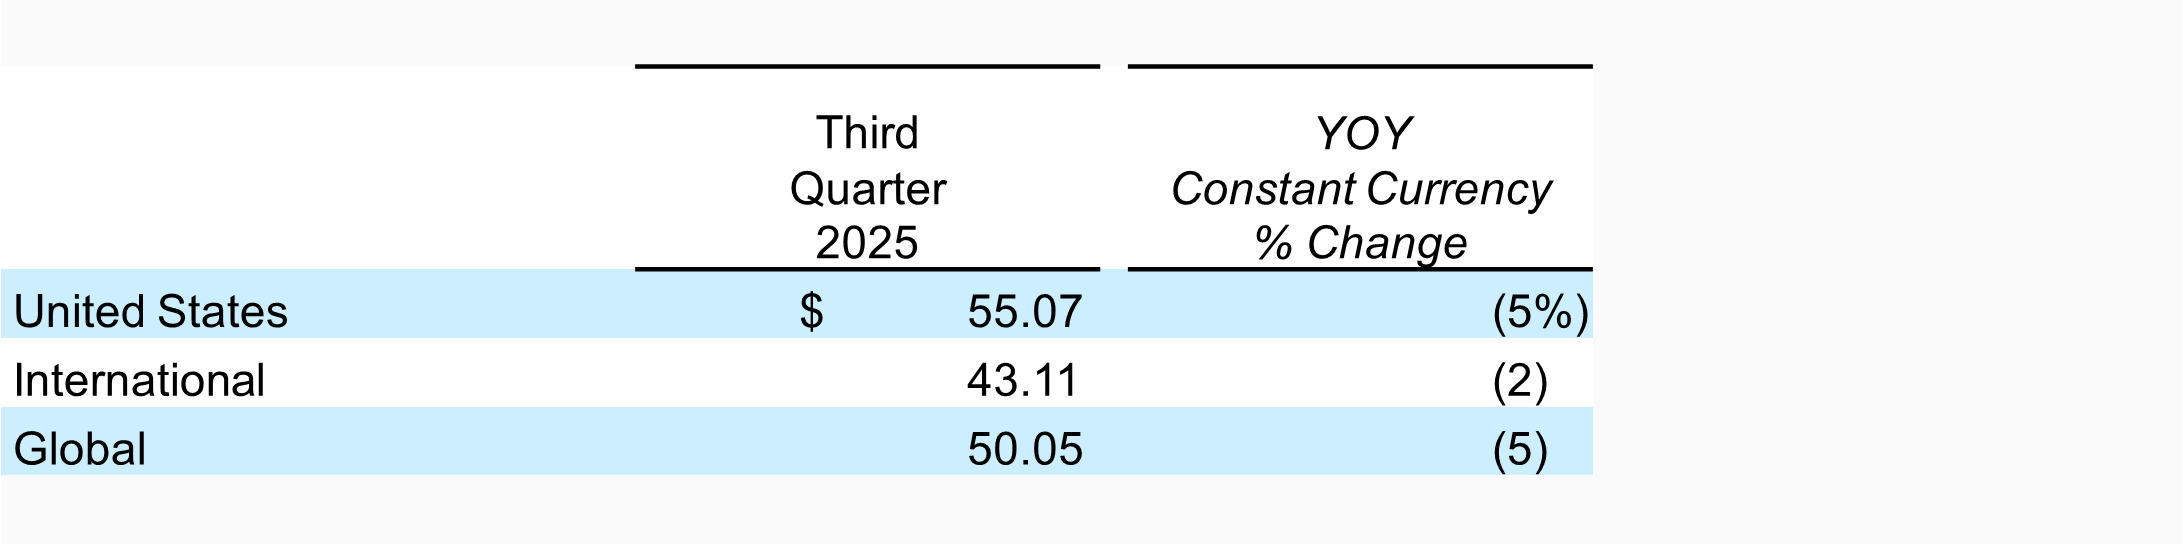
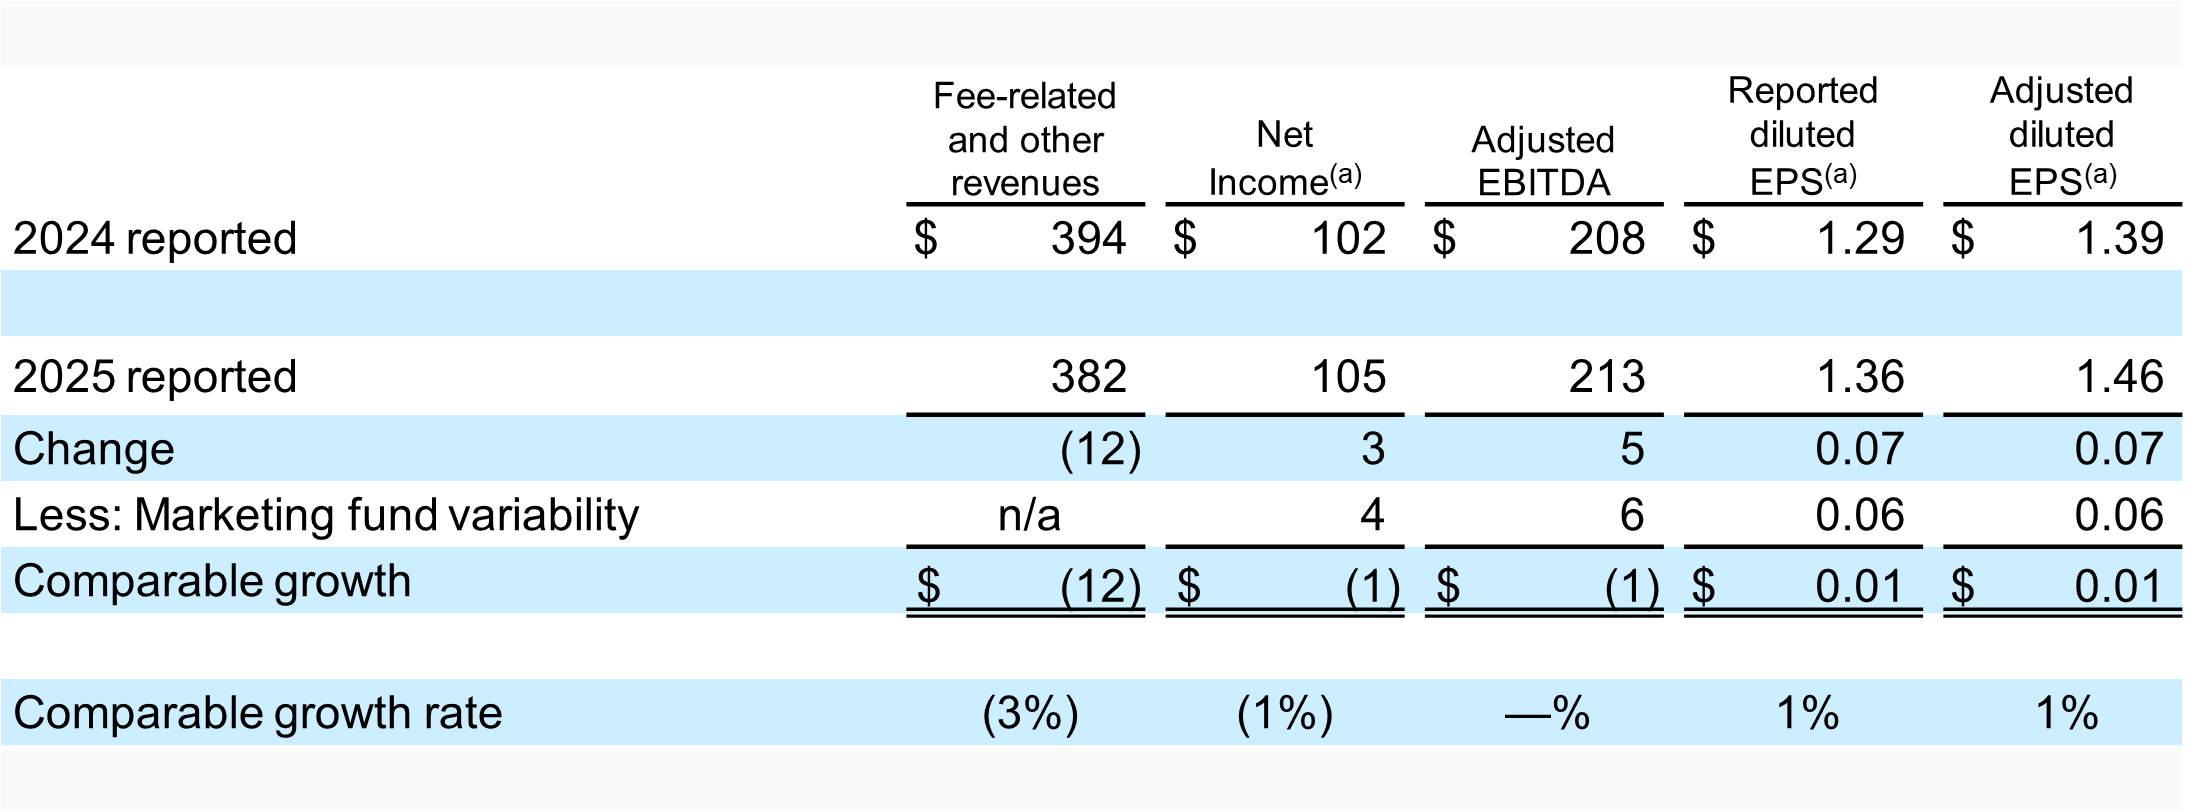
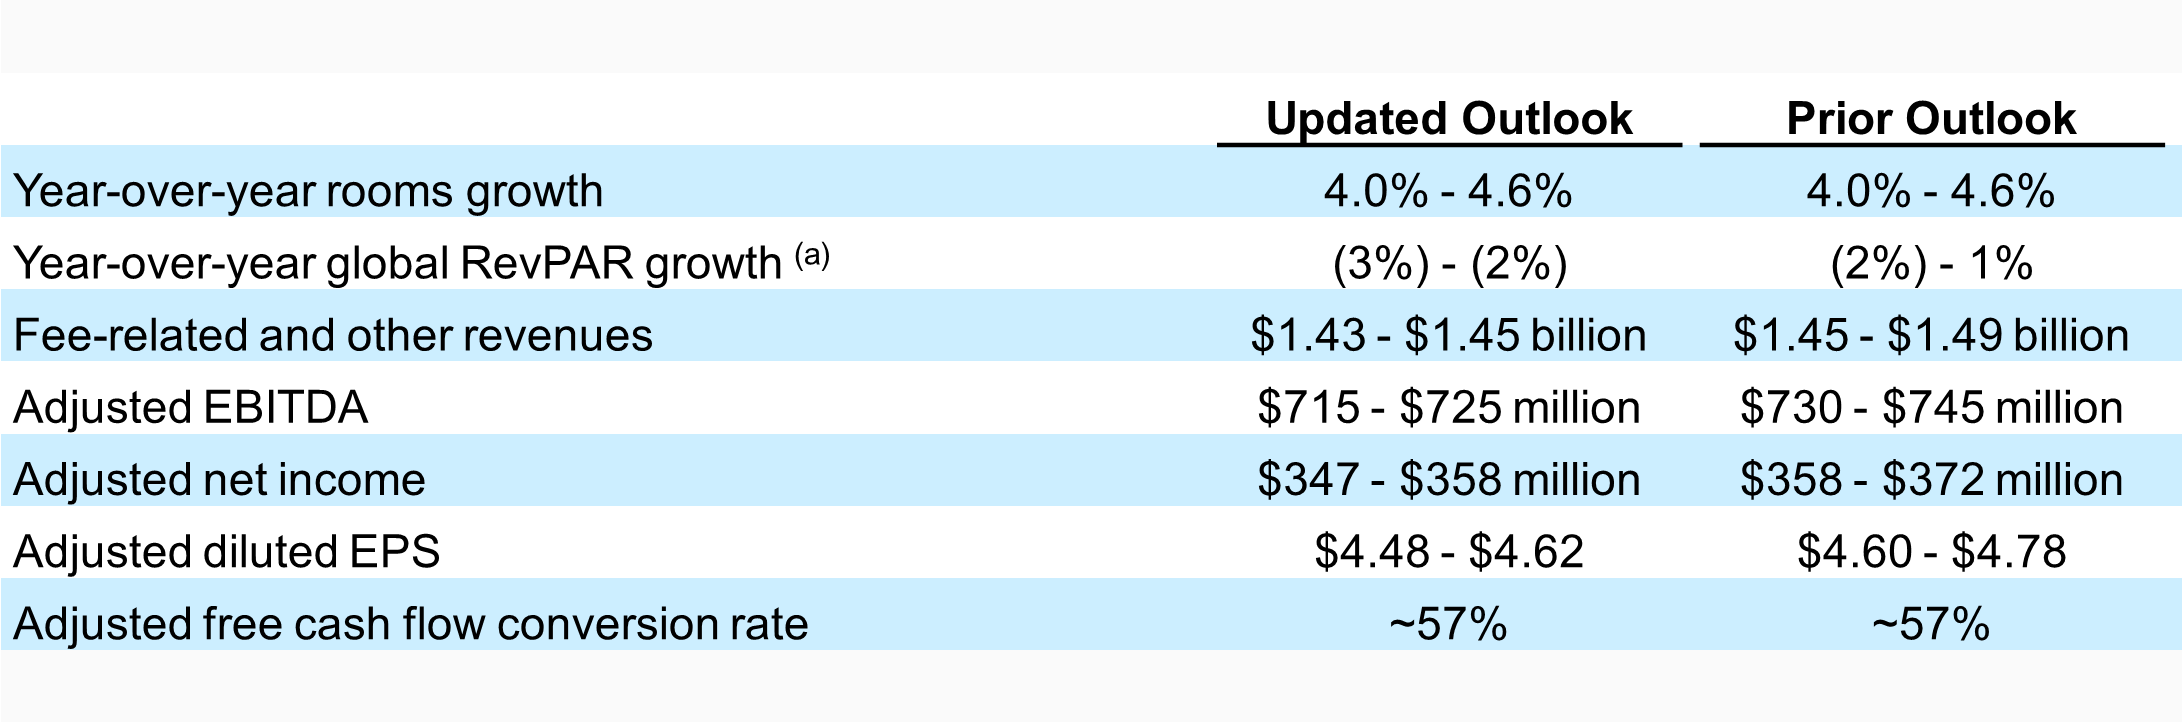 The Company expects marketing fund expenses to exceed revenues by approximately $5 million during full-year 2025, an intentional investment the Company expects to recover in future periods.